Key Takeaways
- Plan N covers the Part A hospital deductible and coinsurance, plus Part B coinsurance, but you pay the $283 Part B deductible, up to $20 office copays, and up to $50 ER copays yourself in 2026.
- Plan N does not cover Part B excess charges (up to 15% above Medicare-approved amounts), so always confirm your provider accepts Medicare assignment before scheduling to avoid surprise bills.
- Plan N typically costs less monthly than Plan G but requires small copays and leaves you exposed to excess charges, while Plan G costs more but covers both—choose based on how often you see doctors.
- You can see any Medicare-accepting provider with Plan N (no network restrictions), making it ideal for keeping a trusted primary care doctor, but verify assignment status before your visit.
- Plan N does not include prescription drug coverage; you must enroll in a separate Part D plan to help pay for medications.
- Preventive care visits like the Annual Wellness Visit are critical with Medigap coverage, but ask how extra diagnostic tests will be billed to avoid unexpected cost-sharing charges.
Choosing how to pay for health care after you turn 65 can feel overwhelming. Original Medicare covers a lot, but it leaves gaps. Those gaps can add up fast, especially if you see your doctor often. That is where Medicare Supplement Plan N comes in. This private Medigap policy helps pay some of the costs that Original Medicare leaves behind.
For many adults, the real question is simple. How will this plan affect my everyday care? Will I pay more when I visit my primary care doctor? What happens if I need a preventive screening or an urgent visit? This guide answers those questions in plain language. We focus on what matters most for your health: how a Medigap plan works alongside primary care and wellness services. You will learn what Plan N covers, what it does not, and how to avoid surprise bills. We also explain how to check that your doctor fits well with your coverage in 2026.
What Is Medicare Supplement Plan N?
Medicare Supplement Plan N is a type of Medigap insurance. Private insurance companies sell it. It works alongside Original Medicare, which includes Part A (hospital insurance) and Part B (medical insurance). Plan N helps pay certain out-of-pocket costs that Original Medicare does not fully cover.
It is important to know what Plan N is not. It is not a Medicare Advantage plan. It does not replace Original Medicare. It also does not include prescription drug coverage. If you want help with drug costs, you need a separate Part D plan.
How Plan N Works With Original Medicare
Here is the basic flow of a medical visit when you have Original Medicare and Plan N:
- You visit a doctor or hospital that accepts Medicare.
- Original Medicare pays its share of the approved cost first.
- Plan N then pays its share of what Medicare leaves behind, based on the plan rules.
- You pay any remaining amounts, such as the Part B deductible or a small copayment.
Because Plan N works with Original Medicare, you are not locked into a plan network. You can generally see any provider or use any hospital that accepts Medicare. That freedom matters if you want to keep a trusted primary care doctor.
Thing #1: What Plan N Covers and What You Still Pay
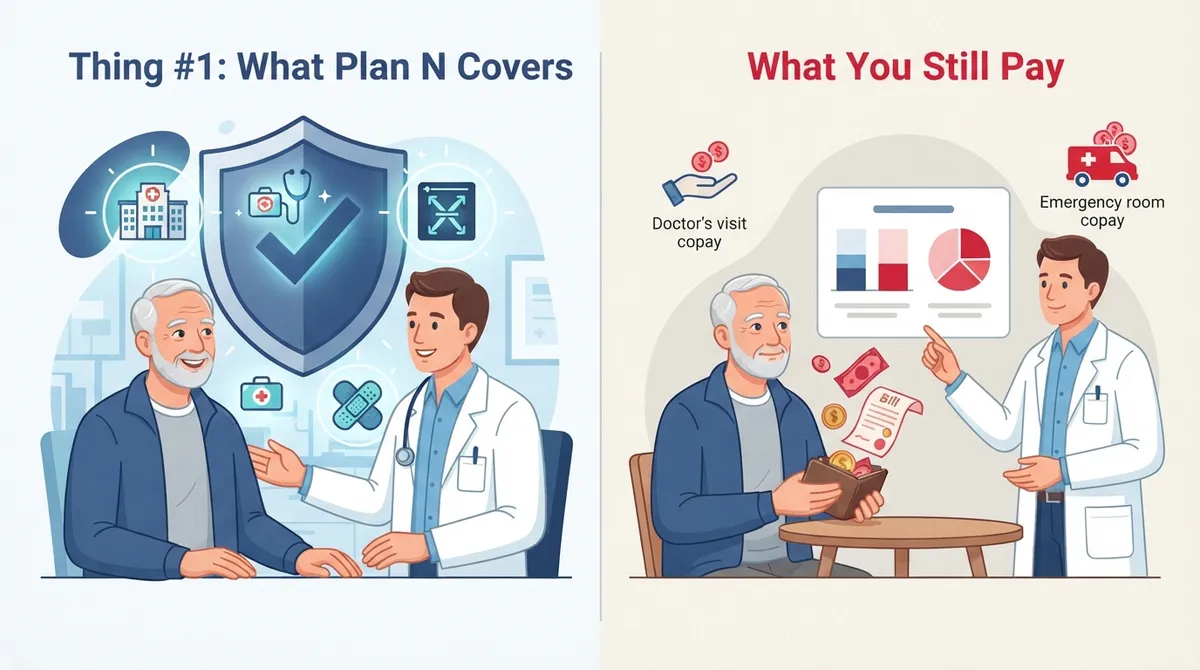
Understanding the cost structure is the most important step. Plan N covers many large expenses. It also leaves a few smaller ones for you to pay. Knowing the difference helps you plan your yearly budget with more confidence.
What Plan N Typically Covers
- Part A hospital deductible: Plan N covers it in full.
- Part A coinsurance: It covers hospital coinsurance, including up to 365 additional hospital days after your Original Medicare benefits run out.
- Part B coinsurance: It covers the 20% coinsurance you would normally owe, subject to the copayments listed below.
- Blood and hospice coinsurance: Plan N helps with these costs as well.
What You Still Pay With Plan N
Plan N does not cover everything. Here is what stays on your side of the bill:
- The Part B deductible: In 2026, the Part B annual deductible is $283, according to the Centers for Medicare & Medicaid Services (CMS).
- Office visit copayments: You may pay up to $20 for some office visits.
- Emergency room copayments: You may pay up to $50 if an ER visit does not lead to a hospital admission.
- Part B excess charges: Plan N does not cover these (more on this below).
- Your Part B premium: The standard 2026 premium is $202.90 per month. Some people pay more based on income.
You also still pay your Plan N premium to the insurance company. Premiums vary by insurer and location, so comparing quotes matters.
A Quick Cost Snapshot
|
Cost Item |
Who Pays With Plan N? |
|---|---|
|
Part A hospital deductible |
Plan N |
|
Part A coinsurance (plus 365 extra days) |
Plan N |
|
Part B coinsurance |
Plan N (after copays) |
|
Part B deductible ($283 in 2026) |
You |
|
Office visit copay (up to $20) |
You |
|
ER copay (up to $50, if not admitted) |
You |
|
Part B excess charges |
You |
|
Prescription drugs |
Separate Part D plan |
Sources for these figures include CMS and the official Medigap guidance from Medicare.gov.
Thing #2: How Plan N Affects Primary Care and Preventive Visits
Most people use primary care more than any other service. So it helps to know how your supplement plan treats those visits. A strong relationship with a primary care doctor can protect your health and keep long-term costs lower. You can read more about this in our guide on what a primary care physician does for your health.
Primary Care Visits and Copayments
With Plan N, you may pay a copayment of up to $20 for some office visits. This copayment applies to certain doctor visits, not every service. Your costs depend on the type of visit and how it is billed. A routine office visit may carry the copay, while some preventive services may not generate any cost-sharing at all.
The Medicare Annual Wellness Visit
Medicare covers many preventive services. One key example is the Annual Wellness Visit. This visit focuses on prevention. Your provider reviews your health history, checks risk factors, and builds a personalized plan. To learn what to expect, see what happens during an annual wellness visit.
There is one catch. If your wellness visit also includes extra diagnostic tests or treatment for a new problem, those added services may create cost-sharing. For example, if your doctor addresses a new symptom during the visit, that portion may be billed like a regular office visit. Ask the office how the visit will be coded before you go. This simple question can prevent a surprise bill.
Why Preventive Care Matters Even More With Medigap
Preventive care lowers the chance of serious illness. Screenings can catch problems early, when treatment is easier and often less costly. Services like cancer screening and routine blood work help you stay ahead of health issues. Plan N helps with the costs that follow if a larger problem does appear. Together, prevention and good coverage give you a strong safety net.
Chronic conditions also benefit from steady primary care. Learn how doctors support long-term health in how primary doctors help manage chronic illnesses.
Choosing a Provider Who Fits Your Plan
With Original Medicare and Plan N, you can see any doctor who accepts Medicare. But not every provider bills the same way. Before you book, confirm two things:
- The provider accepts Medicare.
- The provider accepts Medicare assignment.
Accepting assignment means the provider agrees to take the Medicare-approved amount as full payment. This detail leads directly to the next big topic.
Thing #3: Excess Charges, Plan Comparisons, and Smart Enrollment
The third thing to know is where Plan N can cost you more. It also helps to understand how Plan N compares with other plans and how enrollment works.
Understanding Part B Excess Charges
Part B excess charges can surprise people. They happen when a provider does not accept Medicare assignment. That provider may charge more than the Medicare-approved amount. Federal rules limit this extra charge to 15% above the approved amount, where it is permitted.
Plan N does not cover Part B excess charges. So if you see a provider who does not accept assignment, you pay the extra amount yourself. The fix is simple. Always ask if the provider accepts assignment. Choosing a clinic that works well with Medicare helps you avoid this risk. Our guide on the traits of the best Medicare provider for primary care can help you ask the right questions.
Plan N vs. Plan G: A Quick Look
Many people compare Plan N with Plan G. Both are popular Medigap options. Here is a simple comparison of how they differ for everyday care:
|
Feature |
Plan N |
Plan G |
|---|---|---|
|
Monthly premium |
Often lower |
Often higher |
|
Office visit copay |
Up to $20 for some visits |
None |
|
ER copay |
Up to $50 (if not admitted) |
None |
|
Part B deductible |
You pay |
You pay |
|
Part B excess charges |
Not covered |
Covered |
The trade-off is clear. Plan N often has a lower premium, but you take on small copays and possible excess charges. Plan G usually costs more each month but leaves fewer surprises. Your best choice depends on how often you see the doctor and how much cost certainty you want.
Medigap vs. Medicare Advantage
People often mix up Medigap and Medicare Advantage. They are very different:
- Medigap (like Plan N): Works with Original Medicare. You can generally see any Medicare provider.
- Medicare Advantage: Replaces Original Medicare with a private plan. It may use networks and require referrals.
If you want to learn about the other path, read about Medicare Advantage plans and what primary care patients need to know. For a broader overview of benefits, see what Medicare covers for seniors in primary care.
Enrollment Tips for Plan N
Timing can affect both your options and your price. Keep these points in mind:
- Start with Original Medicare. You need Parts A and B to buy a Medigap policy.
- Know your enrollment window. Your Medigap open enrollment period usually begins when you are 65 or older and enrolled in Part B. During that time, insurers generally cannot deny you coverage or charge more because of your health.
- Expect underwriting later. If you apply outside your open enrollment window, insurers in many states may review your health history. They may deny coverage or price your plan higher.
- Compare total costs. Do not look only at the premium. Add up the Part B deductible, possible copays, and any excess charge risk.
- Check availability. Premiums, pricing methods, and plan availability vary by insurer and location.
Remember that Plan N does not include drug coverage. Review your prescriptions and consider a Part D plan. Our prescription management tips for better health in 2026 can help you stay organized.
How to Use Plan N to Support Your Wellness Goals
Insurance is only one part of good health. The best plan works when you also build a strong care routine. A few simple habits can help you get the most value from your coverage:
- Pick a primary care doctor early. A steady relationship helps your provider spot changes sooner.
- Schedule your yearly wellness visit. Prevention is one of the smartest uses of your Medicare benefits.
- Confirm billing before you go. Ask if the provider accepts Medicare and assignment.
- Track your screenings. Keep a list of dates for key tests and follow-ups.
- Review your plan each year. Your health needs and costs can change.
If you are still searching for the right doctor, our guide on how to find doctors accepting new patients near you offers practical steps.
Why Primary Care Matters Most With Medigap
A Medigap plan helps with costs, but your health still depends on the care you receive. InCare is a personalized primary care and wellness clinic serving Tampa and Riverview, Florida. The team combines modern technology with medical expertise to focus on prevention and whole-body health. Services include primary care, urgent care, cancer screenings, and advanced wellness options. With a 4.8 out of 5 rating from patients on Google, InCare is a strong choice for adults who want proactive, coordinated care. You can see what InCare patients say on Google and learn more about the clinic's approach.
You can also follow InCare on Facebook, Instagram, and TikTok for health tips and updates.
Final Thoughts
Medicare Supplement Plan N can be a smart middle-ground choice. It often offers lower premiums than richer plans while still covering many big costs. The three key takeaways are simple. First, know what Plan N covers and what you still pay. Second, understand how it affects primary care and preventive visits. Third, watch out for excess charges and compare your total expected costs, not just the premium.
Your coverage works best when paired with a trusted primary care team. Ready to build that foundation? Book your appointment with InCare today, or contact our team with any questions about getting started.
FAQs
Q: What does Medicare Supplement Plan N cover?
A: Plan N covers the Part A hospital deductible, Part A coinsurance (including up to 365 extra hospital days), and Part B coinsurance, subject to its office visit and emergency room copayments. You remain responsible for the Part B deductible and any Part B excess charges.
Q: How much are Plan N's doctor and emergency room copayments?
A: Plan N may require a copayment of up to $20 for some office visits. For an emergency room visit that does not result in hospital admission, the copayment may be up to $50.
Q: Does Plan N cover Part B excess charges?
A: No, Plan N does not cover Part B excess charges. These can occur when a provider does not accept Medicare assignment and bills up to 15% above the Medicare-approved amount, so confirm assignment before your visit.
Q: Can I see any primary care doctor with Medigap Plan N?
A: Generally, yes. With Original Medicare and Plan N, you can see any provider or use any hospital that accepts Medicare, rather than being limited to a plan network. Confirm that the provider accepts Medicare and, ideally, assignment.
Q: Does Plan N cover prescription drugs?
A: No, Medigap Plan N generally does not include prescription drug coverage. You would need a separate Medicare Part D plan to help with medication costs.