Key Takeaways
- SilverScript is a Medicare Part D prescription drug plan, not a primary care provider, and it does not cover office visits or lab work.
- For 2026, Part D out-of-pocket spending is capped at $2,100 on covered drugs; premiums and non-covered drugs do not count toward the cap.
- Check each medication against your plan's formulary for its tier and for prior authorization, step therapy, or quantity limits before filling a prescription.
- Use only in-network pharmacies, and confirm whether your plan offers preferred pharmacy pricing or mail-order for long-term medications.
- Ask your doctor about lower-tier alternatives, prior authorization, or formulary exceptions instead of skipping doses or splitting pills to save money.
- Review your plan every fall during open enrollment, since formularies, tiers, and premiums change yearly, and consider the Medicare Prescription Payment Plan to spread costs.
Many Medicare patients leave a doctor's office with a new prescription and no clear idea what it will cost. SilverScript Medicare plans can help with that cost, but only if you understand how they work. SilverScript is a Medicare Part D brand associated with CVS Health. It covers prescription drugs. It does not replace your primary care doctor, and it does not cover office visits or lab work.
In 2026, the rules around Part D have changed in important ways. Costs are capped, and new payment options exist. Still, every plan has its own formulary, pharmacy network, and rules. A drug that is cheap on one plan may be costly or restricted on another.
This guide walks you through how to use SilverScript Medicare with your primary care team. You will learn how to check coverage, avoid surprise costs, and make smart choices with your doctor. Whether you are a new enrollee or helping a parent, these steps will keep your medications affordable and your care on track.
What SilverScript Medicare Actually Covers
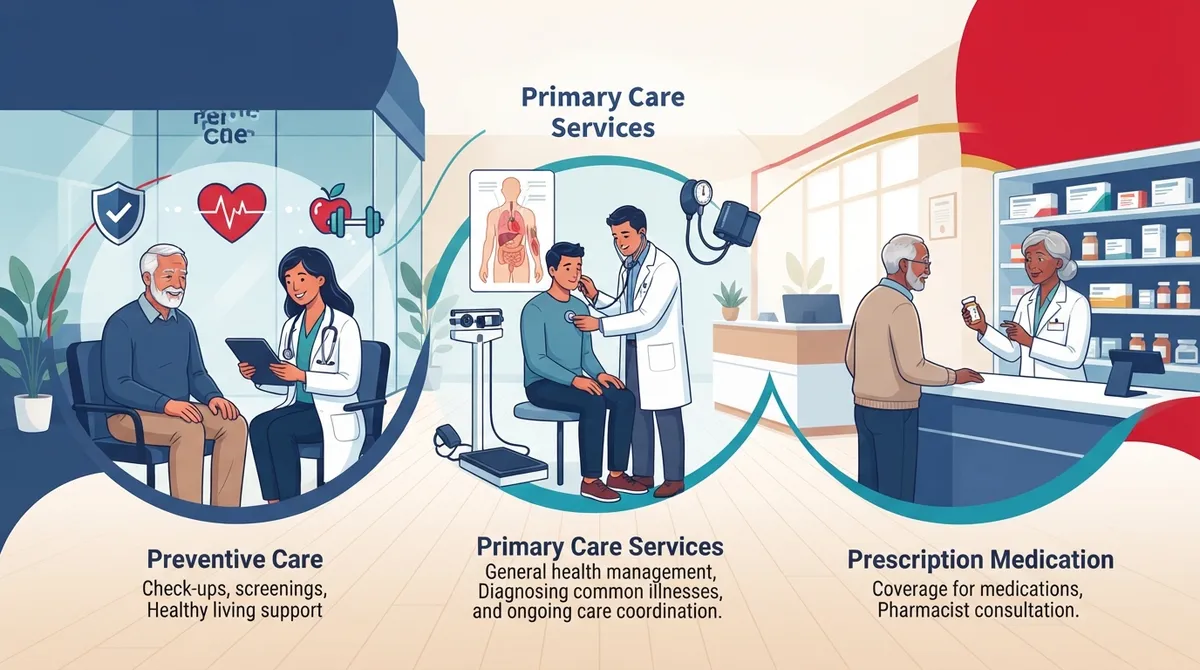
SilverScript is a Medicare Part D prescription drug plan brand. Part D helps eligible Medicare beneficiaries pay for covered prescription drugs. Plan availability, premiums, and benefits depend on the plan and your service area.
It helps to know what SilverScript is not. It is not a primary care provider. It is not general medical coverage. It also does not replace Original Medicare or a Medicare Advantage plan.
How Part D Fits With Other Medicare Coverage
Medicare has several parts, and each covers different things. Mixing them up is a common source of billing trouble.
|
Coverage Type |
What It Generally Covers |
Who Provides It |
|---|---|---|
|
Medicare Part A |
Hospital stays and inpatient care |
Federal Medicare program |
|
Medicare Part B |
Doctor visits, outpatient care, some drugs |
Federal Medicare program |
|
Medicare Part D |
Prescription drugs |
Private plans such as SilverScript |
|
Medicare Advantage |
Medical benefits, often with drug coverage |
Private insurers |
Some drugs are covered under Part B instead of Part D. Certain injectable or infused medications fall into this group. Ask your doctor's office which plan applies before you fill anything.
Key 2026 Changes Every Enrollee Should Know
The Centers for Medicare & Medicaid Services (CMS) updated Part D for 2026. These changes can lower what you pay if you take several medications.
- $2,100 out-of-pocket cap: Once you reach this amount on covered Part D drugs, you pay nothing more for covered drugs for the rest of the year. It was $2,000 in 2025.
- Standard deductible of $615: Under the standard benefit design, you pay this before coverage begins. Your plan's actual deductible may differ.
- 25% coinsurance: The standard benefit design lists this for covered drugs in the initial phase. Actual SilverScript terms may vary.
- Insulin cost sharing: Covered Part D insulin is capped at the lesser of $35 per month's supply, 25% of the maximum fair price, or 25% of the plan-negotiated price.
Remember that premiums and non-covered drug costs do not count toward the cap. Only covered drug spending counts. Always read your plan documents for your exact numbers.
How to Check If Your Medications Are Covered
Coverage depends on the plan's formulary. A formulary is the list of drugs the plan covers. Follow these steps before you enroll, renew, or fill a new prescription.
- Make a full medication list. Include prescriptions, doses, and how often you take each one. Add over-the-counter items your doctor recommends.
- Look up each drug in the plan's drug lookup tool. Use the current plan documents for the year you are in.
- Note the drug tier. Lower tiers usually cost less. Higher tiers cost more.
- Check for restrictions. Look for prior authorization, step therapy, or quantity limits.
- Confirm your pharmacy. Make sure it is in the plan's network.
- Share the results with your doctor. Bring a printout to your next visit.
Plan details change each year. A drug covered last year may move to a higher tier or be removed. Review your plan every fall during open enrollment, even if you are happy with it.
Understanding Formulary Rules
Three rules often surprise patients at the pharmacy counter.
- Prior authorization: Your doctor must get approval from the plan before the drug is covered.
- Step therapy: You must try a lower-cost drug first. The plan covers the next drug only if the first one does not work.
- Quantity limits: The plan caps how much of a drug you can get in a set period.
These rules are not meant to block care. They exist to control costs and promote safe use. But they do add steps. A primary care team that handles these requests quickly can save you days of waiting.
Why Pharmacy Choice Matters
Part D plans generally require network pharmacies for in-network pricing. A pharmacy near your home may not be preferred under your plan. Filling a prescription out of network can raise your cost or leave it uncovered.
Before your doctor sends a prescription, confirm three things:
- The pharmacy is in your plan's network.
- The pharmacy is a preferred pharmacy, if your plan offers lower prices there.
- Mail-order is available if you take long-term medications.
Tell your doctor's office which pharmacy to use. Updating this detail at each visit prevents mistakes. If you want more ideas for keeping prescriptions organized, see these prescription management tips for better health in 2026.
How to Work With Your Primary Care Team
Your primary care doctor is your best partner in keeping drug costs under control. Good communication prevents wasted money and unsafe gaps in treatment.
Bring Your Plan Information to Every Visit
Carry your Part D card or a clear photo of it. Tell your doctor the exact plan name. This lets the clinic check the formulary while you are still in the room. It also helps them reconcile your medications, which means comparing everything you take against what you should be taking.
Ask About Alternatives When Costs Are High
If a prescribed drug is not covered or costs too much, speak up. Your doctor may be able to:
- Suggest a clinically appropriate alternative on a lower tier.
- Submit a prior authorization request.
- Request a formulary exception if no good substitute exists.
Never skip doses or split pills to save money without asking first. That can harm your health. A quick call to your clinic is safer.
Use Preventive Care to Reduce Drug Needs
The best way to lower drug spending is to need fewer drugs. Regular checkups catch problems early. Managing blood pressure, blood sugar, and weight can reduce the number of medications you need over time. Learn how primary doctors help manage chronic illnesses to stay ahead of costly problems.
At InCare primary care in Tampa and Riverview, patients get personalized plans that focus on prevention and whole-body health. InCare physicians review your medication list, discuss coverage questions, and help you choose treatments that fit your clinical needs and your budget. Many patients also benefit from services such as cancer screening and medical weight loss, which support long-term health and may reduce future medication needs.
Ways to Manage Out-of-Pocket Costs
Even with the cap, costs can add up early in the year. Medicare offers tools to smooth out those payments.
The Medicare Prescription Payment Plan
Part D plans must offer the Medicare Prescription Payment Plan. It lets you spread your out-of-pocket prescription costs across the year in monthly payments instead of paying everything at the pharmacy. This can help if you take expensive drugs that would otherwise hit your wallet all at once.
Not everyone benefits equally. If your drug costs are low, it may not change much. Ask your plan or your clinic's staff whether it makes sense for you.
Other Practical Cost Tips
- Ask for a 90-day supply of stable, long-term medications when your plan allows it.
- Compare mail-order and retail pricing for each drug.
- Review your plan each fall, since formularies and premiums change.
- Keep records of what you spend on covered drugs so you can track progress toward the cap.
Common Mistakes to Avoid
Small errors with Part D can lead to big bills. Watch for these:
- Assuming last year's coverage still applies. Always recheck at renewal.
- Using the wrong pharmacy. Network rules affect price.
- Ignoring prior authorization notices. Delays can interrupt treatment.
- Confusing Part B and Part D drugs. The wrong plan may deny the claim.
- Skipping the medication review. Your doctor cannot flag coverage issues if they do not know your plan.
If you want a broader look at working with your insurance and clinic, read about the traits of the best Medicare provider for primary care.
How to Request an Exception or Appeal
If your plan denies coverage, you have options. Follow this process:
- Ask for the denial in writing. It should explain the reason.
- Talk to your doctor. They may support your request with a statement explaining why the drug is medically necessary.
- File an exception or prior authorization request. Your clinic can usually help submit it.
- Follow up on deadlines. Plans must respond within set timeframes, so keep copies of everything.
- Appeal if needed. You can appeal a denial through the plan's process.
A primary care team that handles these requests regularly can move faster and avoid common errors. You can learn more about what Medicare covers for seniors in primary care to understand where drug coverage ends and medical coverage begins.
Who Benefits Most From a Coordinated Approach
Coordinated care matters for everyone, but some patients gain more from it. These groups often see the biggest benefit:
- Adults managing diabetes, high blood pressure, or heart conditions.
- Patients taking five or more medications.
- Caregivers managing a parent's prescriptions and appointments.
- Anyone starting a new, higher-cost medication.
Families often juggle several health plans at once. A single clinic that understands your whole picture saves time and reduces errors. If you are comparing clinics in your area, see how to find the best primary care near you in 2026.
You can also read InCare reviews on Google to see what Tampa Bay patients say about their experience. For updates and health tips, follow InCare on Instagram and Facebook, or watch short wellness videos on TikTok.
Your Next Steps
SilverScript Medicare can make prescriptions more affordable, but only when it is paired with good planning. Start by listing your medications. Check each one against your plan's formulary and pharmacy network. Share the results with your doctor, and review your plan every year.
The goal is simple: get the medicine you need at a price you can manage, without gaps in treatment. A strong primary care relationship makes that much easier.
Ready for a team that looks at your whole health picture? Book your appointment with InCare today, or contact our team with questions about your care. With locations in Tampa and Riverview, InCare is ready to help you stay healthy, informed, and in control of your medications.
FAQs
Q: What is SilverScript Medicare, and is it part of CVS Health?
A: SilverScript is a Medicare Part D prescription drug plan brand associated with CVS Health. It helps eligible Medicare beneficiaries pay for covered prescription drugs. It does not provide primary care or general medical coverage.
Q: How do I check whether my medications are covered by SilverScript?
A: Use the plan's current drug lookup tool or formulary document to search each medication. Note the tier and any rules such as prior authorization, step therapy, or quantity limits. Share the results with your primary care doctor so they can prescribe with your coverage in mind.
Q: What is the 2026 Part D out-of-pocket cap?
A: For 2026, CMS sets the Part D annual out-of-pocket threshold at $2,100. After you reach it, you pay no cost sharing for covered Part D drugs for the rest of the year. Premiums and non-covered drugs do not count toward this amount.
Q: How can I request a formulary exception or prior authorization?
A: Ask your doctor to submit the request to your plan with a statement explaining why the drug is medically necessary. Your clinic can usually handle the paperwork. If the plan denies the request, you can appeal through the plan's process.
Q: How does SilverScript Part D work with Original Medicare or Medicare Advantage?
A: SilverScript Part D is separate from Medicare Part B and from Medicare Advantage medical benefits. Confirm which plan covers a given drug, since some medications fall under Part B instead of Part D. Your primary care office can help you sort this out before you fill a prescription.