Key Takeaways
- Plan N works only with Original Medicare (Parts A and B) and covers Part A hospital coinsurance, the Part A deductible, and most Part B coinsurance, but not the Part B deductible or excess charges.
- Plan N charges small copayments: up to $20 for some office visits and up to $50 for an emergency-room visit that does not lead to admission. Plan G has no such copayments but costs more.
- Enroll during your six-month Medigap Open Enrollment Period, which starts when you are 65 or older and enrolled in Part B, to avoid medical underwriting and possible denial or higher premiums.
- Plan N has no prescription, dental, vision, or hearing benefits, so you will generally need a separate Part D plan and should confirm providers accept Medicare assignment to avoid excess charges.
Medicare is rarely simple, and the choices only multiply once you enroll. Many people reach 65 and ask the same question: how do I keep my doctor visits affordable without surprise bills? For many beneficiaries, a plan n medicare supplement is one answer worth a close look.
Plan N is a type of Medigap policy. It works alongside Original Medicare (Parts A and B) and helps pay some of the costs Medicare leaves behind. Those costs include coinsurance, copayments, and certain deductibles. It does not add new benefits, and it does not replace Medicare.
This guide shows you how to decide if Plan N fits your health and your budget. You will learn what it covers, what you still pay, when to enroll, and how it affects primary care and wellness visits. By the end, you will have a clear process for comparing quotes and choosing a clinic that works smoothly with your coverage.
What a Plan N Medicare Supplement Actually Is
Medigap is private insurance that is standardized by plan letter. Plan N has the same core benefits no matter which insurer sells it. What changes from company to company is the premium and availability. Rules can also vary by state.
Plan N works only with Original Medicare. It is not a Medicare Advantage plan, and it is not a stand-alone health plan. You still need Medicare Part A and Part B, and you still pay your Part B premium.
Think of Original Medicare as the main policy. Plan N is a partner that picks up many of the shared costs after Medicare pays its portion. Medicare pays first. Then Plan N pays its share of what remains.
What Plan N Covers
According to Medicare.gov, Plan N helps pay for the following:
- Part A hospital coinsurance and hospital costs for up to 365 additional days after Medicare benefits are used up
- The Part A deductible
- Skilled nursing facility coinsurance
- Hospice coinsurance or copayments
- Part B coinsurance, subject to Plan N's office-visit and emergency-room copayments
That last item matters most for everyday primary care. Once you meet your Part B deductible, Plan N picks up much of the 20 percent coinsurance that Original Medicare would otherwise leave to you.
What Plan N Does Not Cover
Plan N has limits you should know before you buy. It does not cover:
- The Medicare Part B deductible
- Part B excess charges
- Routine dental, vision, or hearing care
- Outpatient prescription drugs
- Long-term custodial care
You will generally need a separate Medicare Part D plan for prescriptions. Each of these gaps can affect your total yearly spending.
How to Understand the Costs You Still Pay
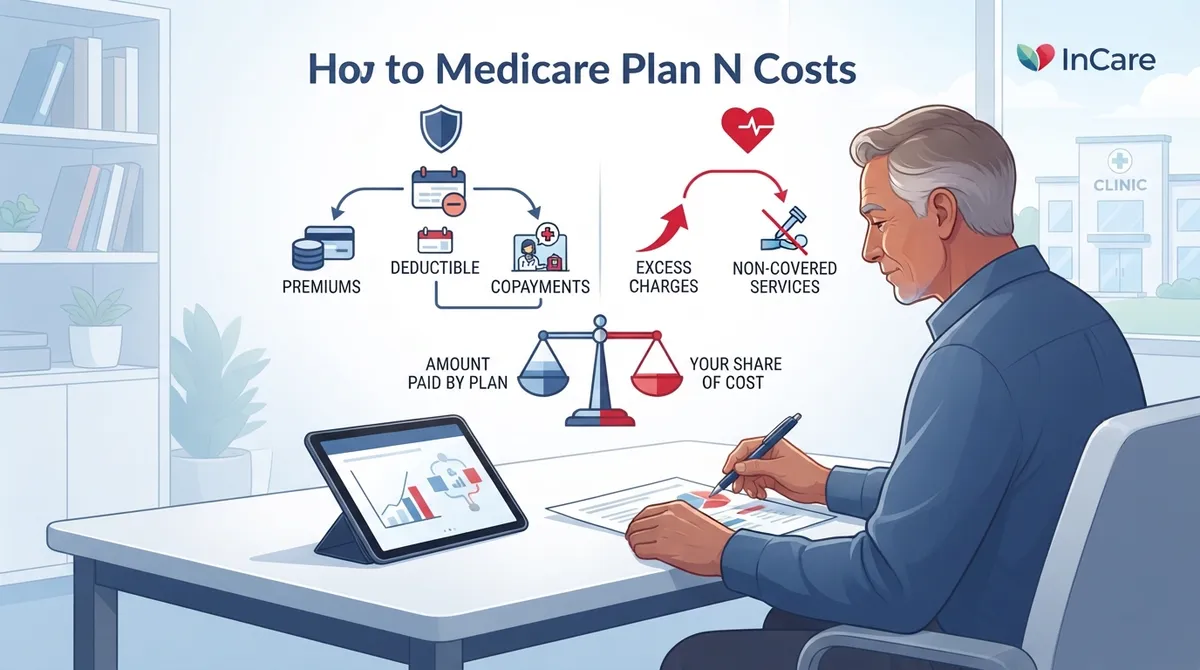
Plan N is designed to lower your risk, not remove all costs. Two features set it apart from richer Medigap plans.
Office Visit and Emergency Room Copayments
With Plan N, you may owe up to $20 for some office visits. You may owe up to $50 for an emergency-room visit that does not lead to a hospital admission. These amounts are modest, and they are predictable.
Part B Excess Charges
Some providers who do not accept Medicare assignment may charge more than the Medicare-approved amount. That extra amount is called a Part B excess charge. Plan N does not pay it. The simplest way to avoid this issue is to choose clinicians who accept Medicare assignment.
|
Cost Item |
Who Pays with Plan N |
|---|---|
|
Part B deductible |
You |
|
Part B coinsurance (20%) |
Plan N, minus copayments |
|
Office visit copayment |
You, up to $20 for some visits |
|
Emergency room copayment |
You, up to $50 if not admitted |
|
Part B excess charges |
You |
|
Part A deductible |
Plan N |
|
Prescription drugs |
Separate Part D plan |
Premiums vary by insurer, location, age-rating method, and other factors. No single national average is reliable. Compare current local quotes before you decide.
How to Know When You Can Enroll Without Medical Questions
Timing is the most important part of buying a Medigap policy. The federal Medigap Open Enrollment Period lasts six months. It begins in the first month you are both 65 or older and enrolled in Medicare Part B.
During this window, insurers generally cannot deny you a policy. They also cannot charge you more because of pre-existing health conditions. After it closes, insurers may use medical underwriting in many cases. That means you could be denied coverage or charged higher premiums.
Some people have guaranteed-issue rights outside this window. State rules may add more protections, so check what applies where you live. Plan the purchase early and do not wait until the last month.
Step-by-Step: How to Choose Plan N
Use this simple process to decide with confidence.
- Confirm your Medicare enrollment. Make sure you have Part A and Part B. Plan N works only with Original Medicare.
- Check your enrollment window. Find the start date of your Medigap Open Enrollment Period and mark the deadline.
- Estimate your yearly care use. List your regular visits, screenings, and ongoing conditions. Frequent visits make copayments add up faster.
- Compare Plan N with other plans. Look at how it compares with Plan G, which has higher premiums but no office-visit copayments.
- Gather local quotes. Get several quotes for the same plan letter. Benefits are the same, so price and insurer service are the differences.
- Verify your providers. Ask each clinician if they accept Medicare and Medicare assignment.
- Add a Part D plan. Choose drug coverage that fits your current prescriptions.
- Apply during your open enrollment window. Submit your application before the deadline to avoid underwriting.
How Plan N Compares With Plan G
Plan G is a common comparison point. Both cover many of the same hospital and Part B costs. The key differences are the copayments and the premium.
|
Feature |
Plan N |
Plan G |
|---|---|---|
|
Premium |
Often lower |
Often higher |
|
Office visit copayment |
Up to $20 for some visits |
None |
|
ER copayment |
Up to $50 if not admitted |
None |
|
Part B excess charges |
Not covered |
Covered |
|
Part B deductible |
You pay |
You pay |
Plan N may suit people who are generally healthy and use care occasionally. Lower premiums can offset small copayments. If you visit doctors often, run the math both ways before you choose.
Can You Use Plan N With Medicare Advantage?
No. Plan N is designed to supplement Original Medicare, not Medicare Advantage. Medigap generally cannot pay Medicare Advantage deductibles, copayments, or coinsurance. Do not treat Plan N as extra coverage to use alongside an Advantage plan. Choose one path or the other based on your needs.
If you want help understanding your options, our guide on Medicare Advantage plans and primary care explains how those plans work. You can also review what Medicare covers for seniors in primary care to see how Original Medicare treats everyday services.
How Plan N Supports Primary Care and Wellness
Plan N does not add services. It makes Medicare-approved services more predictable. That predictability can encourage you to keep up with preventive care instead of skipping visits to avoid bills.
Medicare-approved services may include an annual wellness visit, certain cancer screenings, and chronic condition management. Plan N helps with the cost sharing on many of these. It does not cover services Medicare itself excludes.
Preventive care works best with a doctor who knows you well. Learn what happens during an annual wellness visit so you can prepare. If you manage ongoing conditions, see how primary doctors help manage chronic illnesses.
Choose a Clinic That Works With Medicare
Your coverage is only as useful as the clinic you pair it with. Look for a practice that accepts Medicare, explains costs clearly, and offers same-day access. InCare is a personalized primary care clinic with locations in Tampa and Riverview, Florida. Our team combines modern technology with practical, whole-body care. Patients also rate the experience highly, and you can read InCare reviews on Google to see what they say.
InCare offers primary care, urgent care, cancer screenings, and wellness services under one roof. If you are comparing doctors, our list of traits of the best Medicare provider for primary care can guide your search. You can also learn how to find a doctor that accepts Medicare.
Common Mistakes to Avoid
- Waiting too long. Missing your open enrollment window can lead to denial or higher premiums.
- Ignoring excess charges. Plan N does not pay them, so confirm providers accept assignment.
- Skipping drug coverage. Plan N has no prescription benefit.
- Comparing only price. Consider the insurer's service reputation and rate history.
- Mixing plan types. Do not pair Plan N with Medicare Advantage.
Reliable information helps here. The official source is Medicare.gov's Medigap plan comparison. It lists every plan letter side by side. For free, unbiased counseling, you can also contact your State Health Insurance Assistance Program, found through SHIP.
For local community updates and health tips, you can follow InCare on Facebook.
Conclusion
Plan N can be a smart middle path. It trims many Medicare cost-sharing expenses, keeps premiums moderate, and leaves small, predictable copayments. It will not fit everyone, so weigh your visit habits, your budget, and your provider choices carefully. Most important, act within your six-month open enrollment window.
Once your coverage is set, pair it with a primary care team you trust. If you live in the Tampa Bay area, book an appointment with InCare to start building a prevention-focused care plan. Have questions first? Contact our team and we will gladly help.
FAQs
Q: What does Medicare Supplement Plan N cover?
A: Plan N covers Part A hospital coinsurance, the Part A deductible, skilled nursing facility coinsurance, hospice costs, and most Part B coinsurance. You may owe up to $20 for some office visits and up to $50 for an emergency-room visit that does not result in admission.
Q: Does Plan N cover the Part B deductible or excess charges?
A: No. Plan N does not pay the Medicare Part B deductible or Part B excess charges. To avoid excess charges, choose providers who accept Medicare assignment.
Q: Can I use Plan N with Medicare Advantage?
A: No. Plan N supplements Original Medicare only. Medigap generally cannot pay Medicare Advantage deductibles, copayments, or coinsurance.
Q: When can I enroll in Plan N without medical underwriting?
A: The federal Medigap Open Enrollment Period is a one-time six-month window that starts when you are 65 or older and enrolled in Part B. During it, insurers generally cannot deny you coverage or charge more for pre-existing conditions.
Q: Does Plan N include prescription drug, dental, vision, or hearing coverage?
A: No. Plan N does not cover routine dental, vision, hearing care, or outpatient prescriptions. You will generally need a separate Medicare Part D plan for drug coverage.