Key Takeaways
- Kaiser Medicare Advantage is an HMO or HMO-POS plan that coordinates care within one system, but limits you to in-network providers for routine care—verify your current doctors and specialists are covered before enrolling.
- Compare total yearly costs (premiums + copays + out-of-pocket maximum), not just monthly premiums; a $0 premium plan may have higher copays while preventive care is covered at $0 cost.
- Confirm prescription drug coverage and formulary for your medications, as not all Kaiser Medicare Advantage plans include Part D coverage despite many offering it.
- Enroll only during Medicare's Annual Enrollment Period (October 15 to December 7) unless you qualify for special enrollment, and review your plan's Evidence of Coverage for full rules and exclusions.
Choosing Medicare coverage shapes how you get primary care, screenings, and wellness support for years. Kaiser Medicare Advantage is one option many adults consider, especially those who like a single, connected system. But the plans differ by region, county, and year, so a careful review matters before you enroll.
This guide shows you how to evaluate a Kaiser Medicare Advantage plan in 2026. You will learn what the plans cover, how the network works, which costs to compare, and when you can enroll. You will also see how to think about primary care access, so your plan supports your health goals instead of limiting them.
Whether you are new to Medicare or reviewing your current plan, the steps below will help you make a clear, confident choice.
What Kaiser Medicare Advantage Actually Is
Kaiser Medicare Advantage is Medicare Part C coverage offered through regional plans. It includes your Medicare Part A and Part B benefits. Many plans also include prescription drug coverage. Plan rules, provider access, and cost sharing differ from Original Medicare.
Most Kaiser Permanente Medicare Advantage offerings are HMO or HMO-POS plans. That means you generally use the plan's network for routine care. HMO-POS plans may offer limited out-of-network coverage, but the terms depend on the specific plan.
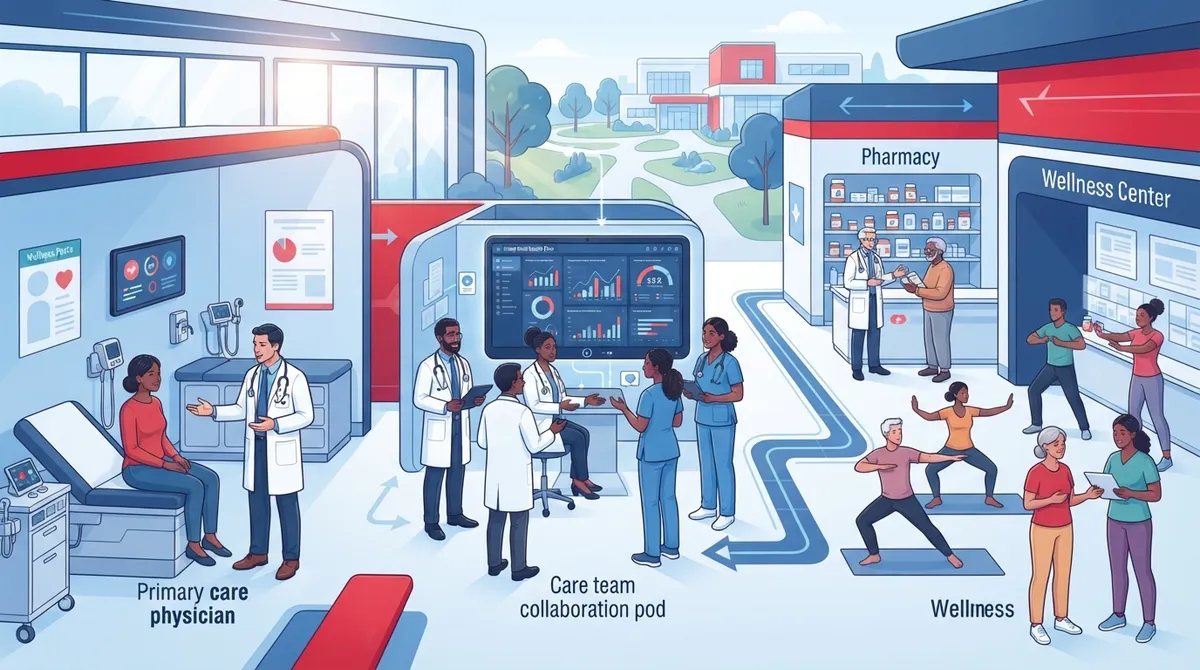
The model is built around coordinated care. Primary care, specialists, labs, pharmacy, and digital tools connect within one system. This can make visits easier to manage. It can also limit your choice of clinicians compared with a broader network.
Step-by-Step: How to Evaluate a Plan
Use this simple process to compare options before you commit.
- Confirm eligibility. You generally need Medicare Part A and Part B and must live in the plan's service area.
- Check your county. Plan names, premiums, and benefits change by region. Do not assume a plan in one state matches another.
- Read the Summary of Benefits. This short document lists copays, premiums, and covered services.
- Review the Evidence of Coverage. This longer document explains the full rules, limits, and exclusions.
- Verify your doctors and drugs. Make sure your clinicians, pharmacy, and medications fit the plan.
- Compare total yearly cost. Add premiums, copays, drug costs, and the out-of-pocket maximum.
Take your time with each step. A few extra hours of review can prevent surprise bills later.
Understand the HMO and HMO-POS Network
The network is the most important part of any Medicare Advantage plan. In an HMO, you usually must use plan providers for non-emergency care. Emergency and urgent care rules still apply, but routine visits typically stay in network.
An HMO-POS plan adds a point-of-service option. This may give you limited out-of-network coverage under plan-specific terms. Always read how much that option covers and what you would pay.
Ask these questions before you enroll:
- Is my current primary care clinician in the network?
- Are the specialists I need available locally?
- What happens if I travel or spend part of the year elsewhere?
- How are urgent care visits covered outside the service area?
Access to particular clinicians and services depends on local network availability and plan rules. If your care team matters to you, confirm this first.
Compare the Costs That Matter
Costs vary widely by plan and location. The figures below come from 2026 Kaiser plan materials and are regional examples only. They are not universal rates.
|
Region (2026 Example) |
Primary Care Visit |
Specialist Visit |
Other Cost Notes |
|---|---|---|---|
|
Virginia (some plans) |
$0 |
$35 |
Another listed plan shows $0 primary care and $40 specialist |
|
Maryland (Care Plus) |
$5 |
$45 |
$28 monthly premium |
|
Washington (various plans) |
Varies |
Varies |
Monthly premiums from $0 to $358 by county and plan |
A 2026 Washington Evidence of Coverage lists a $6,600 annual maximum out-of-pocket amount for the Anchor plan. Limits differ by plan and region, so always check your own documents.
Do not judge a plan by premium alone. A $0 premium plan may have higher copays. A higher premium plan may include richer benefits. Estimate your likely yearly use of care, then compare total cost.
Preventive Care and Wellness Benefits
Preventive care is a central feature of Kaiser Medicare Advantage. Kaiser's 2026 materials list $0 cost sharing for covered preventive care. This includes eligible annual wellness visits and screenings. Coverage frequency and eligibility follow Medicare rules and your plan documents.
Preventive visits help you catch problems early and manage chronic conditions. They also give you time to talk with a clinician about goals, medications, and risk factors. If you want to know what to expect, read what happens during an annual wellness visit. You can also learn how to make preventive care work for your health.
Plans may also offer optional supplemental benefits. These can include dental, hearing, vision, transportation, acupuncture, or chiropractic services. Some come with added premiums or allowances. Benefits vary by plan and location, so confirm what your county offers.
Check Prescription Drug Coverage
Many Kaiser Medicare Advantage plans include prescription drug coverage, but not every plan necessarily includes Part D. Do not assume your plan covers medications. Verify it in the plan documents.
Check these items for each plan:
- Whether the plan includes Part D drug coverage
- The formulary, which is the list of covered drugs
- The pharmacy network and any preferred pharmacies
- Copays and tiers for the medications you take
Good medication management also helps you save money and stay safe. These prescription management tips can help you stay organized.
Know When You Can Enroll
Enrollment is generally limited to Medicare enrollment periods. The Annual Enrollment Period runs from October 15 to December 7. Qualifying circumstances can create special enrollment opportunities. Confirm current dates and eligibility with Medicare or the plan.
Since the date today is in the enrollment window, now is a good time to review your options. Start with your current plan's Annual Notice of Change. Then compare it against any new plan you are considering. Small changes in copays or networks can add up.
Kaiser Medicare Advantage vs. Original Medicare
Many people weigh Medicare Advantage against Original Medicare. The table below shows the main differences in plain terms.
|
Feature |
Kaiser Medicare Advantage |
Original Medicare |
|---|---|---|
|
Coverage type |
Part C plan covering Part A and Part B |
Part A and Part B directly |
|
Network |
Usually HMO or HMO-POS |
Any provider accepting Medicare |
|
Care model |
Coordinated within one system |
Separate, independent providers |
|
Extra benefits |
Varies by plan, such as dental or vision |
Not included in basic coverage |
|
Costs |
Plan premiums and copays |
Part B premium, deductibles, coinsurance |
Neither choice is right for everyone. Your health needs, budget, and preference for provider choice should guide the decision.
Think About Primary Care Access
Your primary care relationship is the foundation of your health. A good primary care clinician tracks your history, manages chronic conditions, and coordinates specialists. When you evaluate any Medicare plan, ask how easy it is to see a primary care clinician and how quickly you can get an appointment.
Some patients value a smaller, personalized practice where they can build a long-term relationship. If that matters to you, review options like a primary care practice that offers longer visits and advanced wellness tools. You can also read about traits of the best Medicare provider for primary care to help you compare.
If you live in the Tampa Bay area, InCare offers personalized primary care, urgent care, cancer screening, and wellness services in Tampa and Riverview. Our team focuses on prevention and whole-body health, using modern technology and clear communication. You can see our locations and learn more about us. Patients also share their experiences, and you can read InCare reviews on Google.
Before you switch to any plan, confirm which Medicare plans your preferred clinic accepts. Our guide on finding a doctor that accepts Medicare walks through the process.
Common Mistakes to Avoid
Many people run into the same problems when choosing a plan. Avoid these:
- Assuming all plans are the same. Benefits differ by county and plan name.
- Ignoring the network. A great plan on paper is not helpful if your clinician is not covered.
- Focusing only on premium. Copays and the out-of-pocket maximum matter just as much.
- Skipping the drug check. Confirm Part D coverage and your formulary.
- Missing the deadline. Mark the enrollment dates on your calendar.
For more help, see these Medicare wellness visit mistakes to avoid.
Quick Checklist Before You Decide
- Confirm you live in the plan's service area.
- Compare the Summary of Benefits for your county.
- Read the Evidence of Coverage for limits and exclusions.
- Check that your doctors, hospitals, and pharmacy are in network.
- Verify drug coverage and your formulary.
- Add up premium, copays, and the out-of-pocket maximum.
- Confirm the enrollment dates with Medicare or the plan.
You can also follow Medicare updates and health tips from InCare on Facebook, Instagram, and TikTok.
Final Thoughts
Kaiser Medicare Advantage can be a strong fit if you like coordinated care inside one system and can use its network. The key is to check the details for your own county and your own health needs. Compare costs, confirm your clinicians, verify drug coverage, and enroll during the right period.
If you want personalized primary care and wellness support in Tampa or Riverview, InCare is here to help you stay healthy and informed. Book your appointment now or contact our team with questions about your Medicare coverage and care options.
FAQs
Q: What does Kaiser Medicare Advantage cover?
A: Kaiser Medicare Advantage covers Medicare Part A and Part B services through a regional plan. Many plans also include prescription drug coverage and optional benefits like dental, vision, or hearing. Coverage details vary by plan and county, so review the Summary of Benefits for your area.
Q: Is Kaiser Medicare Advantage an HMO or a PPO?
A: Most Kaiser Permanente Medicare Advantage offerings are HMO or HMO-POS plans. This means you generally use the plan's network for routine care. HMO-POS plans may provide limited out-of-network coverage under plan-specific terms.
Q: Does Kaiser Medicare Advantage include prescription drug coverage?
A: Many Kaiser Medicare Advantage plans include prescription drug coverage, but not every plan necessarily includes Part D. Always verify the formulary, pharmacy network, and medication costs for your specific plan before you enroll.
Q: When can I enroll in or change a Kaiser Medicare Advantage plan?
A: Enrollment is generally limited to Medicare enrollment periods, including the Annual Enrollment Period from October 15 to December 7. Qualifying circumstances can create special enrollment opportunities. Confirm current dates and eligibility with Medicare or the plan.
Q: What preventive care is covered at no cost?
A: Kaiser's 2026 materials list $0 cost sharing for covered preventive care, including eligible annual wellness visits and screenings. Coverage frequency and eligibility follow Medicare rules and your plan documents, so check your Evidence of Coverage for details.