Key Takeaways
- AARP Medicare Advantage plans are insured or administered by UnitedHealthcare and its affiliates, not AARP itself, so direct coverage questions and claims to the plan.
- Before enrolling, search the plan's provider directory for your exact county and confirm your primary care doctor, specialists, hospital, and pharmacy are in network, then call the office to verify.
- Primary care copays vary widely across plans (examples range from $0 to $10), so compare the official Summary of Benefits for your county rather than assuming a benefit applies.
- Plan type drives referrals and out-of-network access: HMO and HMO-POS plans usually require an in-network PCP, while PPOs generally do not require referrals.
Choosing a Medicare plan is a big decision, and the name on the card matters less than what the plan actually covers. Many people see the AARP name and assume it is the insurer. It is not. AARP Medicare Advantage plans are insured or administered by UnitedHealthcare and its affiliates. That detail shapes your doctor choices, your costs, and your access to preventive care.
For anyone who cares about prevention, wellness, and a strong relationship with a primary care doctor, the details matter most. Costs, networks, and benefits change by county and by plan year. This guide covers six facts every primary care patient should know about AARP Medicare Advantage in 2026. You will learn how plans work, what they may cover, and how to protect your access to the doctors you trust. Our team at InCare sees these questions every day from patients in Tampa and Riverview, Florida.
Fact 1: AARP Medicare Advantage Is Not an Insurer
AARP Medicare Advantage refers to Medicare Advantage plans sold under the AARP name. UnitedHealthcare and its affiliates insure or administer them. AARP is the brand, not the health plan itself.
This matters when you have a question about a claim or a referral. You will work with the plan, not AARP, for coverage decisions. Always read the plan's own documents before you enroll.
What Medicare Advantage Actually Is
Medicare Advantage is also called Part C. These plans must cover everything Original Medicare Part A and Part B cover, subject to Medicare rules. Many also bundle extra benefits into one plan.
- Hospital coverage (Part A) and medical coverage (Part B) are included.
- Many AARP-branded plans also include Part D drug coverage, but not all do.
- Extra benefits may include dental, vision, hearing, and wellness perks.
- Rules, premiums, and benefits vary by plan and by county.
Never assume a benefit applies in every location. The official Summary of Benefits and Evidence of Coverage for your county is the only reliable source.
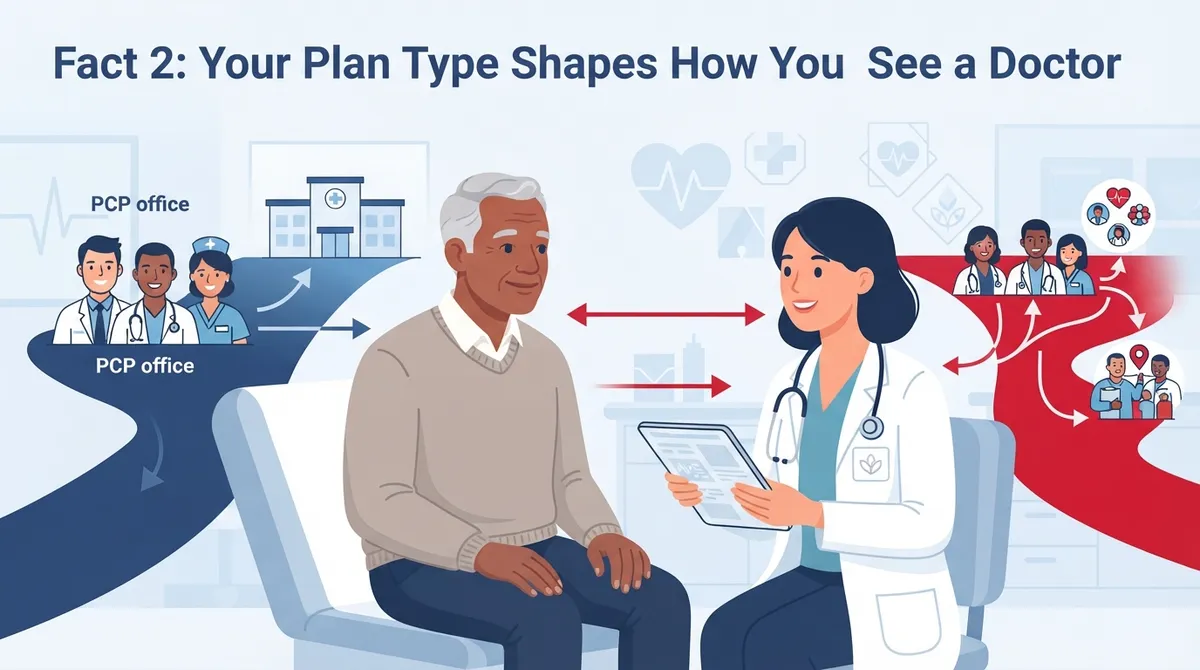
Fact 2: Your Plan Type Shapes How You See a Doctor
Plan type is one of the biggest factors in your day-to-day care. It decides whether you need referrals and whether you can leave the network.
|
Plan Type |
Primary Care Provider |
Referrals |
Out-of-Network Care |
|---|---|---|---|
|
HMO |
Usually must choose an in-network PCP |
Often required for specialists |
Generally not covered, except emergencies |
|
HMO-POS |
Must choose an in-network PCP |
Often required |
Limited coverage for some services |
|
PPO |
PCP not always required |
Generally not required |
Allowed at a higher cost |
|
Special Needs Plan |
Varies by plan |
Varies by plan |
Varies by plan |
Terms differ from plan to plan, so confirm the details in your plan documents. If you want a long-term relationship with one doctor, plan type should be a top factor in your decision.
Fact 3: Primary Care Costs Vary Widely by Plan
Primary care copays are not the same across AARP Medicare Advantage plans. Real 2026 plan documents show how much they can differ.
- One 2026 plan lists a $0 primary care copay, a $25 specialist copay, and $0 network telehealth visits.
- Another 2026 plan lists a $10 primary care copay and $0 network telehealth visits.
- A 2026 HMO-POS plan lists a $0 primary care copay and requires an in-network PCP.
These examples come from specific plans in specific areas. Do not assume they apply to your plan. The plan year runs January 1 through December 31, 2026, so check current documents for exact premiums, deductibles, copays, and out-of-pocket maximums.
Understand the Out-of-Pocket Maximum
Medicare Advantage plans have an annual limit on what you pay for covered Part A and Part B services. This protects you from very high medical bills. The limit differs by plan. It generally does not include Part D drug costs or your monthly premium.
Fact 4: Preventive Care Is a Major Benefit
Prevention is where a strong primary care relationship pays off. Many plans cover preventive screenings and annual physicals at little or no cost when you stay in network. One 2026 plan lists preventive screenings and annual physicals as covered at 100% in network.
Wellness checkups help catch problems early. A good visit reviews your history, medications, screenings, and goals. If you want to know what to expect, read our guide on what happens during an annual wellness visit. You can also learn how to make preventive care work for your health.
Preventive Services to Ask About
- Annual wellness visit and physical exam
- Cancer screenings, such as colon, breast, and prostate checks
- Blood pressure and diabetes monitoring
- Vaccines recommended for your age
- Medication reviews to prevent harmful interactions
Ask your plan which services are covered and how often. Frequency limits can apply. InCare offers cancer screening and full primary care built around early detection and whole-body health.
Fact 5: Provider Networks Decide Whether You Keep Your Doctor
The most common mistake people make is joining a plan before checking the network. A plan can look perfect on paper and still leave your favorite doctor out. Networks also change, so a doctor in network today may not be in network next year.
How to Check Your Network Before Enrolling
- Open the plan's provider directory for your exact plan and county.
- Search for your primary care doctor by name.
- Confirm your specialists and preferred hospital.
- Check that your pharmacy is in the plan's network.
- Call the doctor's office to verify they accept the plan.
A phone call is the safest final step. Directories can be out of date. If you are looking for a provider, our article on the traits of a great Medicare provider can help. You can also read how to find doctors accepting new patients near you.
Fact 6: You Can Only Enroll or Change Plans at Certain Times
Eligibility generally requires Medicare Part A and Part B and a home address in the plan's service area. You can only join or switch during certain Medicare enrollment periods. Missing a window can leave you stuck with a plan that no longer fits.
Plans change every year. Premiums, networks, and benefits can all shift. Review your plan each year, even if you are happy with it.
A Simple Yearly Review Checklist
- Read your plan's annual notice of changes.
- Confirm your doctors are still in network.
- Check your drug list for coverage and cost changes.
- Compare copays for primary care, specialists, and telehealth.
- Look at the out-of-pocket maximum.
Why Primary Care Should Anchor Your Medicare Choice
Your plan pays the bill, but your primary care doctor guides your health. A good doctor coordinates your care, manages chronic conditions, and helps you avoid costly problems. Learn more about how primary doctors help manage chronic illnesses and why coordinated care beats fragmented care.
For many patients, the best plan is the one that keeps a trusted doctor in network. Before you decide, choose the doctor you want, then confirm which plans work with that office. InCare serves patients across Tampa and Riverview with comprehensive primary care, urgent care, and advanced wellness services. You can see what patients say on Google by visiting our InCare location reviews. We hold a 4.8 out of 5 rating from 359 reviews.
Stay connected with our team on Facebook, Instagram, and TikTok for health tips and clinic updates. For official Medicare rules, the government site Medicare.gov is a trusted source.
Conclusion
AARP Medicare Advantage can be a strong option, but the details decide its value. Remember that the plan is run by UnitedHealthcare and its affiliates, that plan type controls referrals and network rules, and that primary care costs vary from plan to plan. Verify your doctor in the directory, read the official Summary of Benefits, and review your coverage every year.
Not sure how your plan works with a primary care team? Contact InCare to ask about coverage and care options, or book your appointment now and start building a care relationship focused on prevention and long-term health.
FAQs
Q: What is AARP Medicare Advantage, and is it the same as UnitedHealthcare?
A: AARP Medicare Advantage refers to Medicare Advantage plans sold under the AARP name. UnitedHealthcare and its affiliates insure or administer them, so AARP is the brand and UnitedHealthcare is the plan behind it. Benefits and costs depend on your county and plan year.
Q: Does AARP Medicare Advantage cover primary care visits and annual physicals?
A: Many plans cover primary care visits and preventive services, and some list low or $0 copays for in-network primary care. These benefits are not the same on every plan. Check your local Summary of Benefits and Evidence of Coverage to confirm what applies to you.
Q: Can I keep my current primary care doctor with an AARP Medicare Advantage plan?
A: You can keep your doctor only if that doctor is in your plan's network, especially with HMO and HMO-POS plans. Search the provider directory for your exact plan and call the office to verify before you enroll. Networks can change from year to year.
Q: When can I enroll in or change an AARP Medicare Advantage plan?
A: You can usually enroll or switch only during specific Medicare enrollment periods. You generally need Medicare Part A and Part B and must live in the plan's service area. Review your plan each year, since benefits, networks, and costs can change.