Key Takeaways
- Anthem Medicare Advantage plans must cover everything Original Medicare Part A and B cover, with many including Part D drugs and extras like dental, vision, and fitness—but verify your specific plan's Summary of Benefits and Evidence of Coverage for exact details.
- Your plan type (HMO vs. PPO) determines network restrictions and specialist access: HMOs require in-network PCPs and referrals with no out-of-network coverage except emergencies, while PPOs allow out-of-network care at higher costs with more freedom.
- Before scheduling appointments, verify your doctor participates in your exact Anthem plan by checking the provider directory and calling the clinic directly—accepting Medicare doesn't guarantee acceptance of your specific plan.
- The federal out-of-pocket maximum for in-network services is $9,250 in 2026, but individual plans may set lower limits; compare total costs including premiums, copays, and out-of-pocket maximums rather than focusing only on monthly premiums.
- Many 2026 Anthem plans offer $0 in-network copays for preventive services like annual wellness visits, cancer screenings, and immunizations—prioritize these low-cost preventive benefits to catch health issues early and avoid costly treatment later.
- A strong primary care doctor coordinates your care across specialists, tracks chronic conditions, and reviews medications to prevent fragmented care and achieve better health outcomes—prioritize finding a trusted PCP within your network.
Choosing a health plan is a big decision. If you or a loved one is eligible for Medicare, you have likely seen ads for Anthem Medicare Advantage. These plans bundle your hospital and medical coverage into one package, and many add extras like dental, vision, and wellness perks. But the details change by county, plan type, and doctor network. That is where many people get stuck.
The good news is that primary care sits at the center of how these plans work. Your primary care doctor is often your first stop for checkups, screenings, and referrals. In this guide, we break down three key things to know about Anthem Medicare Advantage in 2026. You will learn what the plans cover, how doctor networks affect your care, and how to use preventive benefits to stay healthy. We also share simple steps to check your plan before you book a visit.
1. What Anthem Medicare Advantage Actually Covers
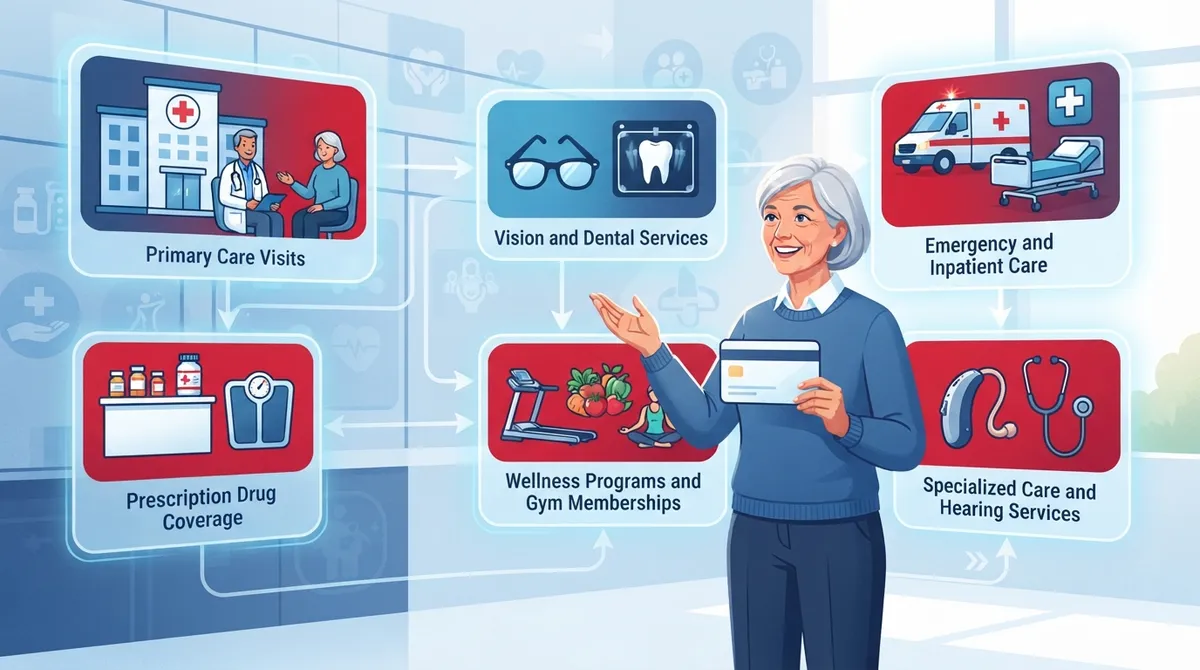
Anthem Medicare Advantage is also called Medicare Part C. It is offered by private insurers but must follow Medicare rules. According to Anthem's plan overview, every plan must cover everything that Original Medicare Part A and Part B cover. Many plans also bundle Part D prescription drug coverage and extra benefits.
The Centers for Medicare & Medicaid Services projected 35.7 million Medicare Advantage enrollees in 2025. That is about 51% of everyone enrolled in Medicare. So if you are considering a plan like this, you are in good company.
Core Coverage You Can Expect
- Hospital care (Part A): inpatient stays, skilled nursing, and hospice.
- Medical care (Part B): doctor visits, outpatient care, and preventive services.
- Prescription drugs (Part D): included in many, but not all, plans.
- Extra benefits: some plans add dental, vision, hearing, fitness programs, and over-the-counter allowances.
Keep in mind that these extras are plan-specific. They may have limits, require participating providers, or come with eligibility rules. Always read the Summary of Benefits and the Evidence of Coverage. These two documents are the final word on what your plan pays.
Costs Vary by Plan and Location
Premiums, copays, and networks differ by county and plan type. Anthem's 2026 materials note that the federal maximum out-of-pocket limit for in-network Medicare Advantage services is $9,250 in 2026. That is down from $9,350 in 2025. Individual plans may set a lower limit, so check your own plan document.
|
Cost Item |
What to Check |
Why It Matters |
|---|---|---|
|
Monthly premium |
Plan Summary of Benefits |
Some plans charge $0, others charge more |
|
Primary care copay |
In-network vs. out-of-network |
Out-of-network visits often cost more |
|
Out-of-pocket maximum |
Federal limit is $9,250 in 2026 |
Caps your yearly in-network spending |
|
Drug coverage |
Formulary and tiers |
Affects what you pay at the pharmacy |
For example, a 2026 Anthem Ohio PPO Summary of Benefits lists a $0 in-network primary care visit copay. It also lists 50% coinsurance for out-of-network primary care visits. These numbers apply to that specific plan only, so do not assume your plan matches.
2. How Your Plan Type and Network Shape Primary Care Access
This is the part that surprises many people. Your plan type decides which doctors you can see and how easy it is to get care. A great plan on paper can feel frustrating if your trusted doctor is not in the network.
HMO vs. PPO: The Main Difference
Anthem offers several plan types. The two you will see most often are HMO and PPO.
- HMO plans: You usually pick an in-network primary care provider (PCP). You may need a referral to see a specialist. Care outside the network is often not covered, except in emergencies.
- PPO plans: You can usually see out-of-network doctors, but you pay more. You often do not need referrals, which gives you more freedom.
- HMO-POS plans: These work like HMOs but may allow some out-of-network services at a higher cost.
If you value a long-term relationship with one doctor, plan type matters a lot. Our guide on how to use a Medicare HMO for better primary care explains how to make an HMO work in your favor.
Why Your Primary Care Doctor Matters So Much
A strong PCP does more than treat colds. They track your blood pressure, manage long-term conditions, review your medicines, and catch problems early. They also coordinate with specialists so nothing falls through the cracks. This is called coordinated care, and it often leads to better results than seeing many doctors who never talk to each other. You can read more in our article on fragmented care vs. coordinated care.
If you live in the Tampa Bay area, a local team can make a real difference. InCare offers personalized primary care with state-of-the-art technology at our Riverview and Tampa locations. Our providers focus on prevention and whole-body health, not just quick fixes.
Verify Before You Book
Here is a simple rule: accepting Medicare is not the same as being in your exact plan's network. A practice might take Original Medicare and one Anthem product but not your specific Anthem plan. Before you schedule, take these steps:
- Find your plan name and member ID on your insurance card.
- Check the provider directory on your insurer's website.
- Call the clinic and ask if they participate in your exact plan.
- Ask whether you need a referral or prior authorization for specific services.
- Confirm the clinic is accepting new patients.
Our team shares more tips in how to find doctors accepting new patients near you.
3. How to Get the Most From Preventive and Wellness Benefits
Prevention is where Medicare Advantage can really shine. Catching a problem early is almost always easier, cheaper, and less stressful than treating it late. Many Anthem plans make preventive care very affordable.
Preventive Services Often Listed in Anthem Plans
Anthem plan materials list a wide range of preventive services. Coverage follows Medicare rules and your plan terms, but common examples include:
- Annual wellness visits
- Immunizations, such as flu and pneumonia shots
- Cancer screenings
- Cardiovascular screenings
- Diabetes screening and education
- Obesity counseling
- Tobacco-cessation counseling
Some 2026 plan documents show $0 in-network copays for preventive screenings and annual physical exams. For instance, a 2026 Anthem California HMO-POS Summary of Benefits lists a $0 in-network copay for preventive screenings and annual physicals. It also lists a $500 annual maximum for specified preventive dental benefits. Again, this is one plan, not every plan.
Not sure what happens at these visits? Read our guides on what happens during an annual wellness visit and what happens during an annual physical exam. Many people mix these up. If you want to avoid common errors, see 9 Medicare wellness visit mistakes you must avoid.
Go Beyond the Basics
A basic checkup is a great start. But proactive patients often want more insight into their health. At InCare, we pair standard preventive care with advanced tools that help you see the full picture. Depending on your needs and your plan, you may explore services such as:
- Cancer screening for early detection
- Body composition analysis with 3D imaging
- DNA gene testing for personalized health insights
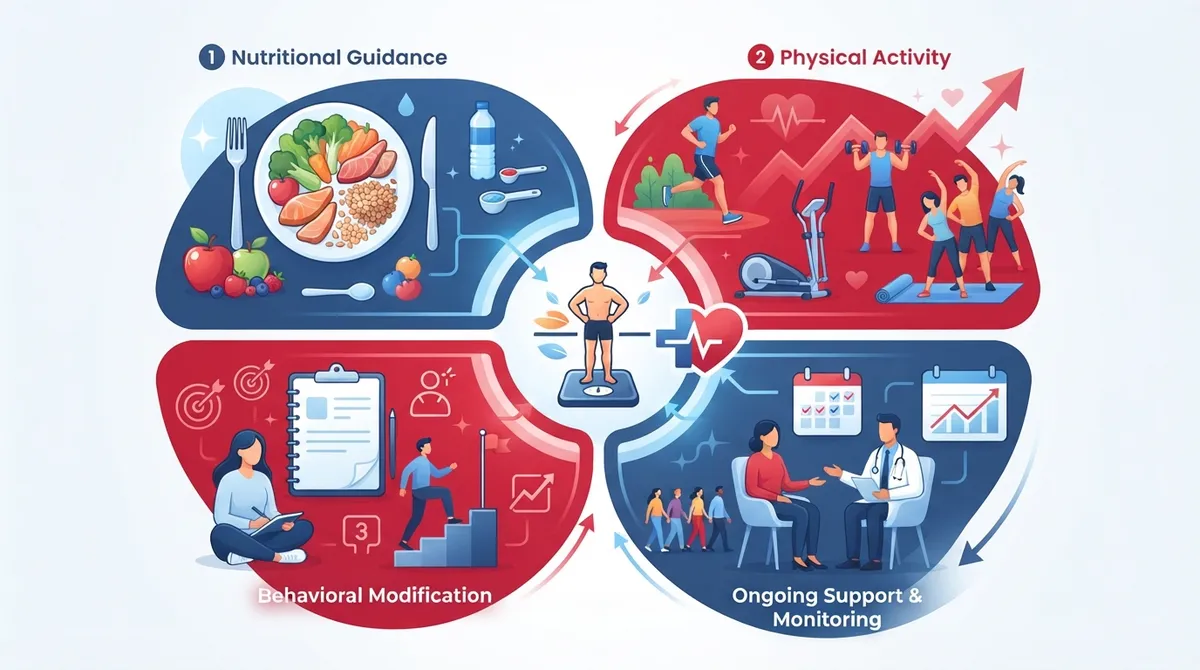
- Medical weight loss programs guided by a physician
Please note that not every wellness service is covered by Medicare or Medicare Advantage. Some are offered as self-pay options. Ask our team what applies to your situation, and we will explain your costs up front.
Why This Matters for Different Patients
Medicare Advantage planning is not only for seniors. Many adult children help their parents choose plans. Busy families, tech-savvy millennials, and wellness-minded professionals often manage care for older relatives. If that is you, a clinic with virtual visits, clear communication, and a coordinated approach can save you time and stress. InCare offers telemedicine along with in-person visits so you can stay connected to your care team from home.
Smart Checklist Before You Enroll or Switch
Open enrollment can feel rushed. Use this quick checklist to stay calm and make a confident choice.
- List your doctors. Make sure your primary care doctor and key specialists are in the network.
- List your medicines. Check that each drug is on the plan's formulary and note the tier.
- Compare total costs. Look at premiums, copays, and the out-of-pocket maximum, not just the monthly price.
- Review extras. Dental, vision, hearing, and fitness benefits can add real value, but read the limits.
- Confirm referral rules. Know whether you need approval to see a specialist.
- Read the Evidence of Coverage. It is long, but it is the authority on your benefits.
If you are comparing plan types, our article on how to compare Medicare HMO vs. Medicare Advantage can help you sort through the differences. You may also like 7 traits of the best Medicare provider for primary care.
Why Local, Personalized Primary Care Makes a Difference
Insurance gets you in the door. A great care team keeps you healthy. When you choose a primary care practice, look for one that listens, explains things clearly, and offers modern tools. At InCare, we combine medical expertise with technology to deliver care that feels personal. Patients praise our friendly staff and thoughtful providers, and our clinic holds a 4.8 out of 5 rating on Google. You can read InCare reviews on Google to see what neighbors in Tampa and Riverview are saying.
Want to see how we work? Meet our providers or learn more about InCare. You can also follow us on Instagram, Facebook, and TikTok for health tips and clinic updates.
Conclusion: Make Your Plan Work for Your Health
Anthem Medicare Advantage can be a smart way to get coverage and extra benefits in one plan. But the value depends on three things: what your plan covers, how your network works, and how well you use your preventive benefits. Always check the plan documents, confirm your doctor is in-network, and book your yearly visits.
If you want a trusted local team to guide your care, we are here to help. Book your appointment with InCare today or contact our team with questions about your coverage. Your health deserves a partner who puts you first.
FAQs
Q: What does Anthem Medicare Advantage cover?
A: Anthem Medicare Advantage plans must cover everything that Original Medicare Part A and Part B cover. Many plans also include Part D prescription drug coverage and extras like dental, vision, hearing, and fitness benefits. Review your plan's Summary of Benefits for exact details.
Q: Do I need to choose a primary care doctor with an Anthem Medicare Advantage HMO?
A: In many HMO plans, you must select an in-network primary care provider and may need referrals to see specialists. PPO plans usually allow you to see out-of-network doctors at a higher cost. Check your specific plan document to confirm the rules.
Q: Are annual wellness visits and preventive screenings free with Anthem Medicare Advantage?
A: Some 2026 Anthem plans list $0 in-network copays for preventive screenings and annual physical exams, but this is not universal. Costs depend on your plan, the service, and whether the provider is in-network. Verify your benefits before your visit.
Q: How can I find a primary care doctor who accepts Anthem Medicare Advantage?
A: Use the provider directory on your insurer's website, then call the clinic to confirm they accept your exact plan. Accepting Medicare does not always mean accepting every Anthem plan. Also ask if the practice is taking new patients.