Key Takeaways
- Lumico Medicare Supplement (Medigap) covers coinsurance, copayments, and deductibles left by Original Medicare, but does not replace Medicare, add drug coverage, or include routine benefits beyond what Medicare allows—most users need a separate Part D plan for prescriptions.
- Lumico Medigap plans offer no network restrictions, allowing you to see any Medicare-accepting provider without referrals, which is especially valuable if you manage chronic conditions or need frequent care and want continuity with one doctor.
- Plan G typically costs more but covers Part B excess charges, while Plan N has lower premiums but includes copayments (up to $20 for office visits, $50 for ER) and does not cover excess charges—choose based on how often you use care.
- Lumico's Medigap policies are guaranteed renewable regardless of health changes, and 2022-2023 data showed Lumico complaint rates 7% below the Medigap average with 85.2% of premiums spent on member benefits versus the 80.4% industry average.
Choosing how to pay for care after 65 is a big decision. Many people compare a Lumico Medicare Supplement plan with Original Medicare alone. Both can work. But they work very differently when it comes to your primary care and wellness needs.
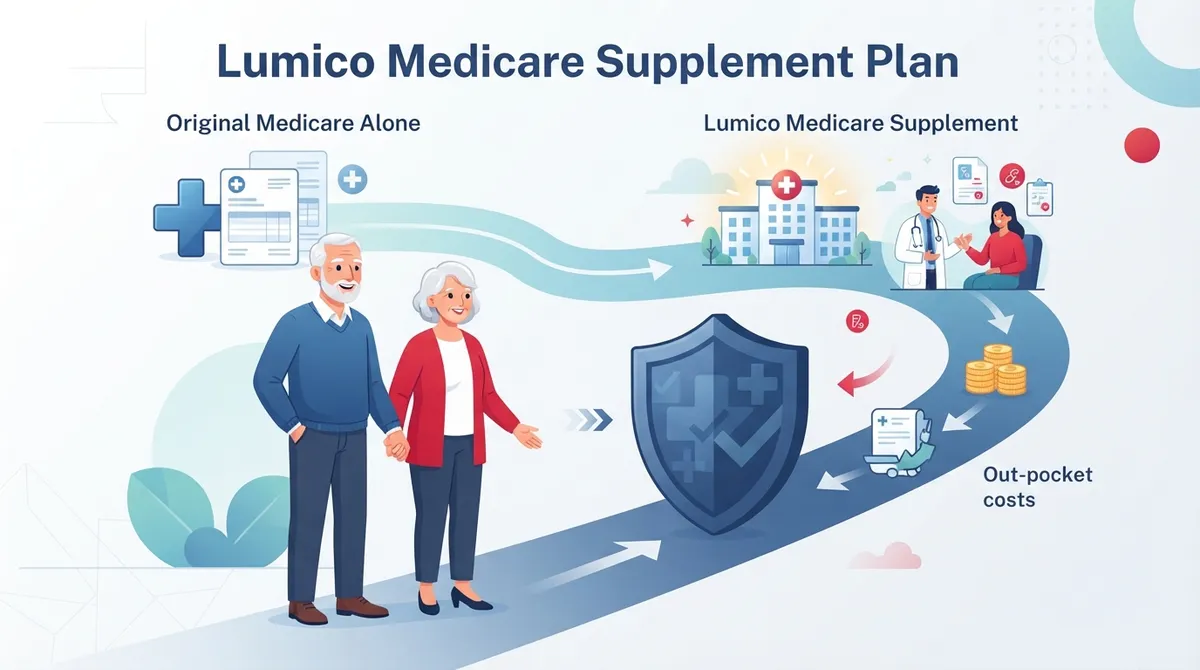
Original Medicare Parts A and B cover many services. They still leave you with deductibles, coinsurance, and copayments. A Lumico Medicare Supplement plan, also called Medigap, helps pay some of those costs. It does not replace Medicare. It works alongside it.
This guide compares the two paths in plain language. You will see what each one covers, where the gaps are, and how it affects your access to a doctor you trust. You will also learn what a Medigap plan does not include, such as drug coverage and routine wellness extras. Whether you are newly eligible or reviewing your coverage in 2026, this comparison will help you ask better questions and plan smarter.
What Is a Lumico Medicare Supplement Plan?
A Lumico Medicare Supplement plan is private Medigap insurance. It pays some of the costs that Original Medicare leaves behind. These can include coinsurance, copayments, and deductibles. The exact help you get depends on the plan letter you pick and the rules in your state.
Lumico's official materials list Plans A, F, G, N, and High-Deductible Plan G. Availability and policy terms can vary by state. They can also change over time. Always confirm current offerings with the insurer or your state insurance department before you enroll.
What a Medigap plan is not
It helps to know what this coverage will not do. A Medigap plan is not Medicare Advantage. It does not replace Original Medicare. It also does not add new benefits that Medicare itself excludes.
- It does not include outpatient prescription drug coverage.
- It does not add routine benefits beyond what Medicare allows.
- It generally does not cover services Medicare does not cover.
Because of this, most people with Medigap also buy a separate Part D plan for prescriptions.
Original Medicare Alone: What You Still Pay
Original Medicare is a strong base. Yet it has no yearly out-of-pocket limit. Without added coverage, you pay a share of each covered service. For primary care, this usually means the Part B deductible and then 20% coinsurance for many outpatient services.
For someone who sees a doctor often, those costs can add up. They matter most for people who manage chronic conditions, need frequent testing, or have a procedure during the year.
Where Original Medicare shines
- Lower upfront monthly cost, since there is no extra premium beyond Part B.
- Broad access to doctors who accept Medicare.
- No separate plan network to learn.
The trade-off is less protection against surprise bills. That is where a supplement enters the picture.
Side-by-Side Comparison
The table below shows how the two approaches differ in everyday terms.
|
Feature |
Original Medicare Alone |
With a Lumico Medicare Supplement |
|---|---|---|
|
Cost-sharing (coinsurance, copays) |
You pay these yourself |
Plan pays some or all, based on plan type |
|
Doctor choice |
Any provider who accepts Medicare |
Any provider who accepts Medicare |
|
Referrals needed |
No |
No |
|
Prescription drugs |
Needs separate Part D plan |
Not included; needs separate Part D plan |
|
Extra routine benefits |
Limited |
Not added by Medigap |
|
Monthly premium |
Part B only |
Part B plus Medigap premium |
Doctor Access: A Key Strength of Medigap
One big feature stands out for primary care. Lumico says its Medigap plans have no network restrictions. You can see providers who accept Medicare, and you do not need referrals. Original Medicare's own provider rules still apply.
This matters if you want a long-term relationship with one doctor. You are not locked into a narrow list. You can choose a clinic that fits your life and health goals.
That kind of freedom pairs well with a practice that offers comprehensive primary care and whole-body wellness services. If you are weighing options, our guide on the traits of the best Medicare provider for primary care can help you compare practices.
Lumico Plan G vs. Plan N
Two plans draw the most questions. They are Plan G and Plan N. Both help with many Medicare costs, but they differ in key ways.
Plan G
- Covers Part B excess charges.
- Does not cover the Part B deductible.
- Usually has a higher premium than Plan N.
Plan N
- Often has a lower premium.
- Generally includes office-visit copayments of up to $20.
- Includes an emergency-room copayment of up to $50 when you are not admitted to the hospital.
- Does not cover Part B excess charges.
If you visit your doctor often, a small copay can add up. If you rarely need care, a lower premium may fit better. The right pick depends on how you use care.
High-Deductible Plan G and Plan F
High-Deductible Plan G has a lower premium. In return, you pay Medicare-covered costs up to a deductible first. For 2026, Medicare.gov lists that deductible as $2,950. Check the current figure for your exact policy and year, since deductibles can change.
Plan F is more limited. It is generally available only to people who became eligible for Medicare before January 1, 2020. Newly eligible people cannot buy a Medigap plan that covers the Part B deductible, including Plan F.
How to Compare Your Options: A Simple Process
- List your care habits. Count your yearly doctor visits, tests, and prescriptions.
- Check your enrollment window. The federal Medigap Open Enrollment Period generally lasts six months. It starts when you are 65 or older and enrolled in Part B.
- Compare plan types. Review Plans A, G, N, and High-Deductible G for your state.
- Ask how premiums are set. Premiums, underwriting rules, and discounts depend on the policy and state.
- Add drug coverage. Pair your plan with a Part D plan if you take prescriptions.
- Confirm your doctor accepts Medicare. Then book a visit to start a care relationship.
Renewal, Reputation, and What the Data Says
Lumico's help materials say Medigap policies are guaranteed renewable as long as you pay premiums. That means the company cannot drop you just because your health changes.
A 2025 NerdWallet review, citing 2022–2023 NAIC complaint data, reported that Lumico and Elips Medigap complaints ran about 7% below the Medigap average. It also reported they spent about 85.2% of Medigap premiums on member benefits, versus an 80.4% industry average. The review estimated the two companies together covered about 60,000 Medigap members, or roughly 0.27% of the market.
Treat these as historical, combined-company figures. They are not a quote or a promise. They are one data point to weigh with your own research.
Wellness Goes Beyond Insurance
Medigap helps with costs. It does not deliver health on its own. Good outcomes come from prevention, screening, and a doctor who knows you well.
This is where the right clinic makes the difference. At InCare, patients can access advanced tools that support whole-body health. These include cancer screening, DNA gene testing, and body composition analysis. The clinic also offers medical weight loss programs and IV hydration therapy. Coverage rules vary, so ask the clinic which services your plan may help pay for.
For a deeper look at what a yearly visit includes, read what happens during an annual wellness visit. You can also learn what Medicare covers for seniors in primary care.
Who Should Choose Which Path?
A Lumico Medigap plan may fit you if:
- You want predictable costs and fewer surprise bills.
- You value free choice of doctors with no referrals.
- You expect to use care often or manage a chronic condition.
Original Medicare alone may fit you if:
- You are healthy and see a doctor rarely.
- You want to keep monthly costs as low as possible.
- You are comfortable paying your share when care is needed.
Neither choice is wrong. The best one matches your health, budget, and comfort with risk. Reviewing it each year is smart, because your needs can change.
Stay Connected and Informed
Health news and coverage tips change often. You can follow InCare on Facebook, see wellness updates on Instagram, or watch short health tips on TikTok. You can also read patient feedback by choosing to visit InCare on Google. With a 4.8 out of 5 rating from 359 reviews, patients often praise the friendly staff and the quality of care at both the Tampa and Riverview locations.
Conclusion
A Lumico Medicare Supplement plan and Original Medicare alone both give you access to doctors who accept Medicare. The main difference is cost-sharing. Medigap pays part of what Medicare leaves behind, but it adds no drug coverage or new routine benefits. Original Medicare alone costs less each month but leaves more risk on you.
Whichever path you choose, pair it with a primary care team that focuses on prevention and personal service. InCare offers that approach in Tampa and Riverview, with in-person and virtual visits. If you want a partner for your long-term health, Book Now to start your care journey, or Contact our team with questions about getting started.
FAQs
Q: What does a Lumico Medicare Supplement plan cover?
A: A Lumico Medicare Supplement plan, also called Medigap, helps pay certain Medicare costs such as coinsurance, copayments, and deductibles. The exact help depends on the plan letter and your state. It does not cover services Medicare itself excludes.
Q: Can I see any doctor with a Lumico Medigap plan?
A: Lumico states its Medigap plans have no network restrictions. You can see providers who accept Medicare and you do not need referrals. Original Medicare's provider rules still apply.
Q: Does Lumico Medicare Supplement include prescription drug coverage?
A: No. Medigap plans do not include outpatient prescription drug coverage. Most people add a separate Medicare Part D plan to cover their medications.
Q: What is the difference between Lumico Plan G and Plan N?
A: Plan G covers Part B excess charges but not the Part B deductible. Plan N often costs less per month, may require office-visit copays of up to $20 and an ER copay of up to $50, and does not cover Part B excess charges.
Q: When can I enroll in a Medigap plan without health questions?
A: The federal Medigap Open Enrollment Period generally lasts six months. It begins when you are 65 or older and enrolled in Part B. Rules and enrollment rights vary by policy and state, so confirm details with the insurer.