Key Takeaways
- State Farm Medicare Supplement (Medigap) only covers eligible out-of-pocket costs that Medicare already approves, such as deductibles and coinsurance—it does not expand what Medicare covers or replace it entirely.
- Enroll during your Medigap Open Enrollment Period (typically when you turn 65 and join Medicare Part B) to avoid denial or higher premiums based on health conditions.
- Many preventive services including annual wellness visits have no cost-sharing when requirements are met, but additional diagnostic or problem-focused services in the same visit may trigger cost-sharing that your supplement can help cover.
- State Farm Medicare Supplement does not cover prescription drugs, dental, vision, hearing aids, or long-term care—you need a separate Medicare Part D plan for prescription drug coverage.
- Plan availability, benefits, and premiums vary significantly by state; confirm with State Farm what plan letters are available where you live before enrolling.
- Medigap and Medicare Advantage are fundamentally different: Medigap works with Original Medicare, while Medicare Advantage replaces it and generally cannot be used together.
If you are enrolled in Original Medicare, you have probably noticed that it does not pay for everything. Deductibles, coinsurance, and copayments can add up fast, even for routine doctor visits. That is why many people look at Medigap plans, including a State Farm Medicare Supplement policy, to help fill those gaps.
But a supplement plan is only one piece of your health coverage. It works alongside Medicare and your primary care team. Knowing how all three fit together can save you money, reduce surprises, and help you get the care you need.
This guide explains what a State Farm Medicare Supplement plan is, what it may cover, and how it relates to primary care and wellness services in 2026. It also shows you how to check your coverage before you book a visit. Whether you are new to Medicare or reviewing your options, you will find clear, practical steps below.
What Is a State Farm Medicare Supplement Plan?
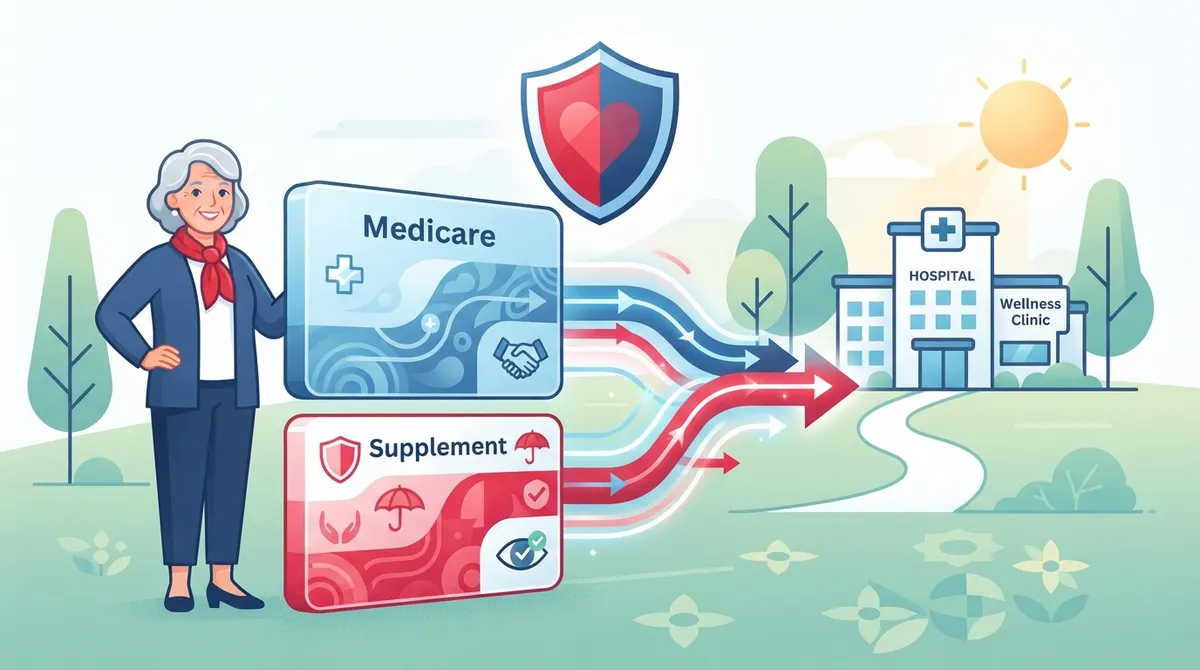
A State Farm Medicare Supplement plan is a type of Medigap insurance. Medigap is private insurance that works with Original Medicare, which includes Part A (hospital) and Part B (medical). Medicare pays its share first. Then your supplement may pay some of the remaining costs for Medicare-covered services.
Those remaining costs often include:
- The Part B deductible
- The 20% coinsurance for many Part B services
- Hospital copayments and coinsurance
- Other cost-sharing, depending on the plan type
State Farm describes offering six standardized Medigap plan types. Which plans you can buy depends on your state, since availability, eligibility, and policy terms vary. State Farm also says it does not offer health insurance in Massachusetts, New Jersey, or Rhode Island. Always confirm what is offered where you live.
Why Standardized Plans Matter
Medigap plans are standardized by letter. In most states, a Plan G from one insurer offers the same basic benefits as a Plan G from another. What changes is the premium, the customer service, and how the company handles rate increases. That means you can compare benefits by letter and then compare prices and service.
How Medigap Fits With Your Primary Care
Primary care is the base of good health. It includes checkups, screenings, chronic condition management, and help with new symptoms. Original Medicare Part B covers medically necessary doctor services and many preventive services.
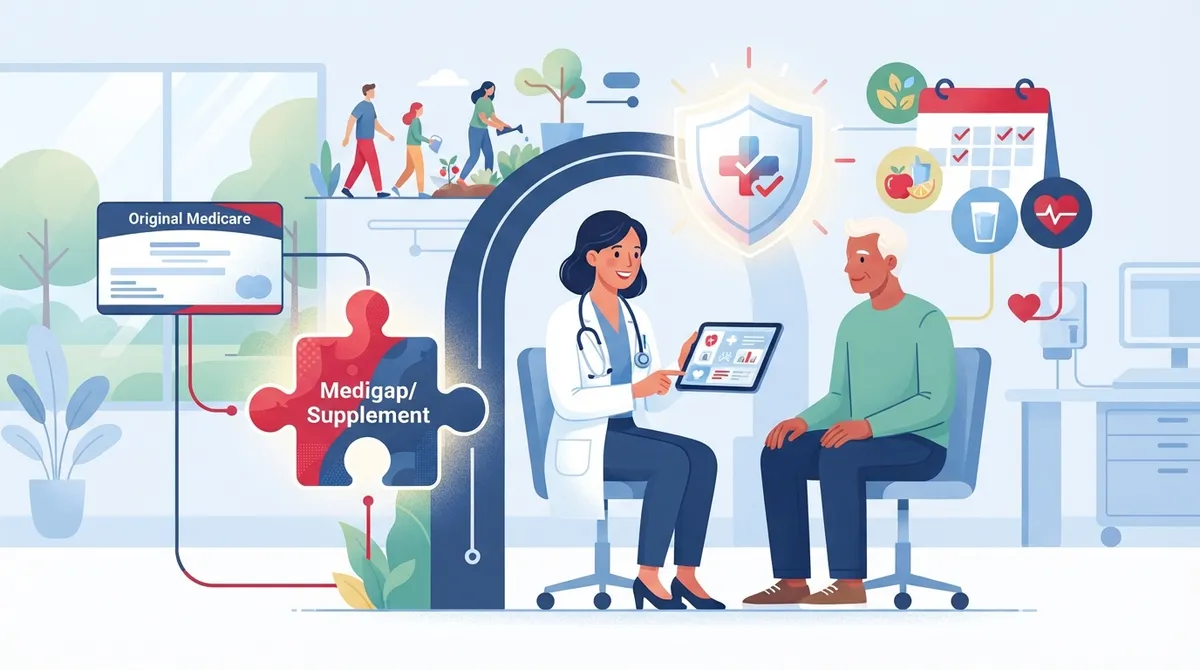
A Medigap policy does not change what Medicare covers. It only helps with eligible out-of-pocket costs for services that Medicare already approves. If Medicare does not cover a service, a supplement generally will not cover it either.
For example, think about a visit to manage high blood pressure. Medicare Part B may cover the visit. After you meet your deductible, you would normally owe 20% of the Medicare-approved amount. A supplement plan may pay some or all of that share, depending on the plan type. You can learn more about what Medicare covers for seniors in primary care before your next appointment.
2026 Medicare Costs to Keep in Mind
Knowing the numbers helps you see where a supplement may help. Here are key 2026 figures from Medicare.gov:
|
Item |
2026 Amount |
What It Means |
|---|---|---|
|
Part B annual deductible |
$283 |
You pay this before Part B starts paying for most services |
|
Part B coinsurance |
20% of the Medicare-approved amount |
Applies to most covered services after the deductible when the provider accepts assignment |
|
High-deductible Plan F and G deductible |
$2,950 |
You pay this before the policy begins to pay covered benefits; availability varies by state |
Plans C and F generally are not available to people who became newly eligible for Medicare on or after January 1, 2020. If you are new to Medicare, plans like G or N may be the options you see most often.
Preventive Care: What Is Covered and What Is Not
Many Medicare-covered preventive services may have no cost-sharing when you meet coverage rules and your provider accepts assignment. This includes the yearly Wellness visit. These visits help you and your doctor build a plan to stay healthy.
There is one catch. If your doctor also treats a new problem or does a separate diagnostic service during the same visit, you may owe cost-sharing for that part. This is where a supplement plan can help, since it may pay part of the cost for those added services.
To get the most from your visit, read about what happens during an annual wellness visit. You can also avoid common errors by reviewing these Medicare wellness visit mistakes.
Tips to Avoid Surprise Bills
- Ask whether your visit is billed as preventive, problem-focused, or both
- Bring a short list of concerns so they can be addressed in a separate, planned way
- Confirm that your provider accepts Medicare assignment
- Review your Medicare Summary Notice after each visit
What a State Farm Medicare Supplement Does Not Cover
Medigap policies are focused on filling cost-sharing gaps. They are not all-in-one health plans. Generally, Medigap does not cover:
- Routine dental care
- Routine vision care and eyeglasses
- Hearing aids
- Long-term care
- Prescription drugs
If you want outpatient prescription coverage, you generally need a separate Medicare Part D plan. This is a common point of confusion. A supplement plan and a drug plan are two different products, and you may need both.
Managing medicines well also matters for your health. These prescription management tips can help you stay organized and safe.
Medigap vs. Medicare Advantage
People often mix up Medigap and Medicare Advantage. They are very different.
|
Feature |
Medigap (Supplement) |
Medicare Advantage |
|---|---|---|
|
Works with |
Original Medicare (Parts A and B) |
Replaces Original Medicare |
|
Main purpose |
Pays some cost-sharing Medicare leaves behind |
Provides your Medicare coverage through a private plan |
|
Provider network |
Generally any provider that accepts Medicare |
Often limited to a plan network |
|
Prescription drugs |
Not included; separate Part D plan needed |
Often included |
Medigap generally requires enrollment in Original Medicare Parts A and B. It generally cannot be used to pay Medicare Advantage cost-sharing while you are enrolled in an Advantage plan. If you are weighing both paths, this guide on Medicare Advantage plans for primary care patients can help you compare.
How to Enroll in a Medicare Supplement Plan
Timing matters when you buy a Medigap policy. Your best window is usually your Medigap Open Enrollment Period. It generally starts when you are 65 or older and enrolled in Medicare Part B. During this time, insurers typically cannot deny you coverage or charge more because of health problems.
Follow these steps to enroll with confidence:
- Confirm your Medicare enrollment. You need both Part A and Part B for Medigap.
- Check availability in your state. Ask State Farm which plan types you can buy where you live.
- Pick the plan letter that fits your needs. Think about how often you see doctors and how much cost-sharing you want covered.
- Compare premiums and service. Benefits are standardized by letter, but prices can differ.
- Add a Part D plan if needed. This helps with prescription drugs.
- Keep your documents. Save your policy and Medicare cards for visits.
Questions to Ask Before You Choose a Plan
Before you sign up, a short list of questions can prevent costly surprises. Consider asking:
- Which plan letters are available in my state?
- How are premiums set, and how do they change over time?
- Is there a high-deductible option, and how does the $2,950 deductible work?
- What is the process for filing and paying claims?
- How does the plan work with my current doctors?
Call State Farm and Medicare directly to confirm policy-specific benefits and costs. Details can differ by state and by plan year.
How to Verify Coverage at a Primary Care Visit
Good primary care starts with clear communication. Before your visit, make a quick checklist. This keeps your costs predictable and your care on track.
- Bring both cards. Have your Medicare card and your supplement card ready.
- Ask about participation. Confirm that the clinic accepts Medicare.
- Clarify the visit type. Ask what is preventive and what may be billed as a separate service.
- Remember what is not covered. A supplement does not make non-covered services covered.
Choosing the right provider also helps. These tips on the traits of the best Medicare provider for primary care can guide your search.
How InCare Supports Medicare Patients in Tampa and Riverview
InCare is a personalized healthcare clinic in Tampa and Riverview, Florida. The team combines modern technology with medical expertise to deliver primary care, urgent care, and advanced wellness services. The focus is on prevention and whole-body health, which fits well with the preventive benefits in Original Medicare.
Patients can get help with annual wellness visits, chronic condition management, and cancer screening. The clinic also offers tools such as DNA gene testing and body composition analysis to build a plan around your goals. If you live in Riverview, you may also find this guide to a Medicare doctor in Riverview, FL useful.
InCare maintains a 4.8 out of 5 rating on Google, and patients often mention the friendly staff and quality care. You can read InCare reviews on Google to see what neighbors say. You can also follow the team on Instagram, Facebook, and TikTok for health tips and clinic news.
Remember, your supplement plan and your clinic work together. The clinic delivers the care. Medicare pays first. Your supplement may then help with eligible out-of-pocket costs.
Key Takeaways
- A State Farm Medicare Supplement plan is Medigap insurance that works with Original Medicare.
- It may reduce eligible out-of-pocket costs, but it does not change what Medicare covers.
- Many preventive services, including the yearly Wellness visit, may have no cost-sharing when requirements are met.
- Medigap generally does not cover drugs, dental, vision, hearing aids, or long-term care.
- Availability, benefits, and premiums vary by state, so always verify before you enroll.
Take the Next Step Toward Better Coverage and Care
A State Farm Medicare Supplement plan can add peace of mind by helping with the costs Original Medicare leaves behind. Pair it with a trusted primary care team, and you can focus on staying healthy instead of worrying about bills. Start by confirming your plan details, then build a prevention-focused routine with your doctor.
Ready to see a primary care team that puts your whole-body health first? Book your appointment with InCare today, or contact our team with questions about Medicare visits and wellness services in Tampa and Riverview.
FAQs
Q: Does State Farm offer Medicare Supplement insurance in my state?
A: State Farm sells Medicare Supplement (Medigap) policies in many, but not all, states. Plan choices, eligibility, and terms vary by state, and State Farm says it does not offer health insurance in Massachusetts, New Jersey, or Rhode Island. Check with State Farm to confirm what is available where you live.
Q: Does Medigap cover primary care doctor visits?
A: Medigap may help pay eligible cost-sharing for primary care visits that Original Medicare already covers, such as the Part B deductible or 20% coinsurance, depending on your plan type. It does not replace Medicare or decide which services Medicare covers.
Q: Will a Medicare Supplement plan cover my Medicare Wellness visit?
A: The yearly Wellness visit is often covered by Medicare with no cost-sharing when requirements are met and the provider accepts assignment. If a separate diagnostic or problem-focused service happens during the same appointment, you may owe cost-sharing, which your supplement may help cover.
Q: Does a State Farm Medicare Supplement cover prescriptions, dental, vision, or hearing aids?
A: Generally, no. Medigap policies typically do not cover routine dental or vision care, hearing aids, long-term care, or prescription drugs. If you want outpatient drug coverage, you generally need a separate Medicare Part D plan.
Q: What is the difference between Medigap and Medicare Advantage?
A: Medigap works alongside Original Medicare to pay some leftover costs, while Medicare Advantage is a private plan that replaces Original Medicare. Medigap generally cannot be used to pay Medicare Advantage cost-sharing while you are enrolled in an Advantage plan.