Key Takeaways
- Always verify your doctor is in-network using the BCBS provider directory and by calling their office directly before enrolling, as networks change frequently and relying on websites alone can lead to coverage gaps.
- Review the full cost picture beyond monthly premiums, including PCP copays, specialist visits, deductibles, and out-of-pocket maximums, since a low premium plan can cost more overall with high copays.
- Understand that referrals and prior authorization are different requirements; ask your PCP and plan which services need approval to avoid surprise bills and denied claims.
- Your primary care provider is the hub of an HMO and coordinates all your care, manages chronic conditions, and reduces repeated tests and conflicting prescriptions through coordinated care.
- Blue Cross Blue Shield is a group of independent local companies, so plan benefits, networks, and costs vary significantly by state and county; always check your specific location and plan year.
- Most BCBS Medicare Advantage HMOs require using in-network providers for non-emergency care; out-of-network visits without approval may result in full out-of-pocket costs.
Choosing a Medicare plan is a big decision. It shapes which doctors you can see, how much you pay, and how easily you get care. A Blue Cross Blue Shield Medicare Advantage HMO is one popular option, and it works very differently from Original Medicare. If you plan to stay healthy and catch problems early, you need to know how this plan treats primary care.
This guide explains how a Blue Cross Blue Shield Medicare Advantage HMO works in 2026. You will learn about networks, referrals, costs, and preventive benefits. You will also learn how to check that your doctor is covered before you enroll. The goal is simple: help you pick a plan that fits your health needs and your daily life.
What Is a Blue Cross Blue Shield Medicare Advantage HMO?
A Medicare Advantage plan is also called Medicare Part C. Private insurance companies offer these plans. They must cover everything Original Medicare Part A and Part B cover. Many also include Part D drug coverage and extra benefits.
An HMO is a Health Maintenance Organization. It uses a defined network of doctors, hospitals, and other providers. You usually pick a primary care provider (PCP) who coordinates your care.
Blue Cross Blue Shield is not one single company. It is a group of independent, locally run companies. Because of this, plan names, benefits, networks, service areas, and costs change by state and county. A plan in Michigan can look very different from a plan in Rhode Island or Texas. Always check the details for your own location and your own plan year.
How a BCBS Medicare Advantage HMO Works
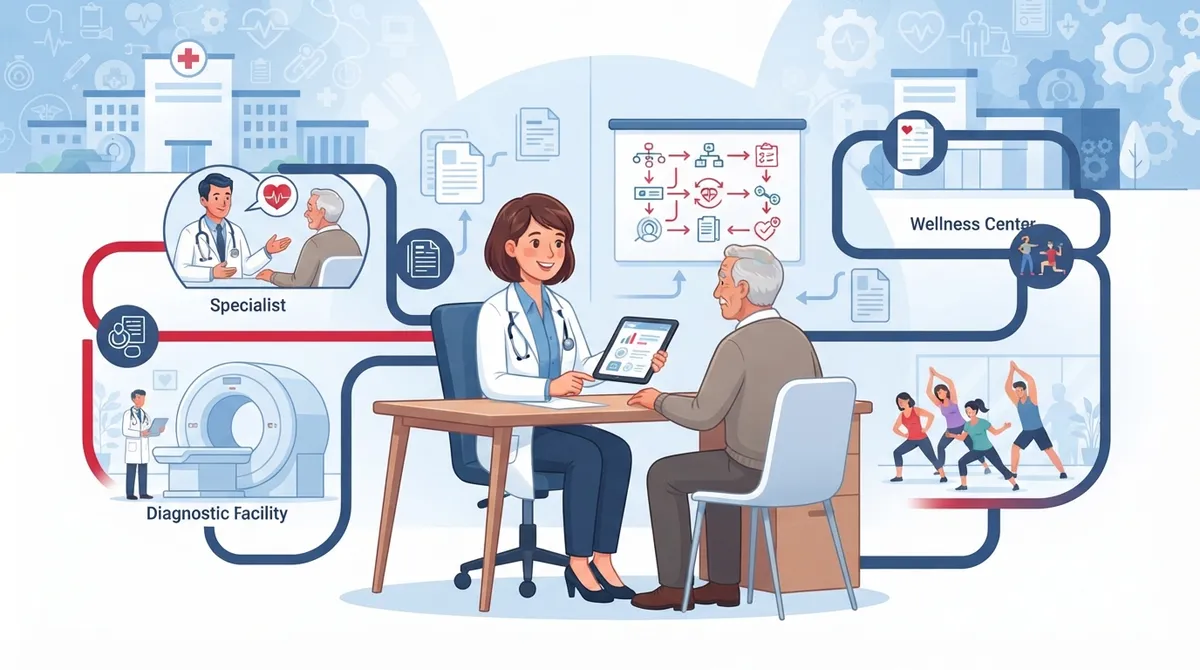
The HMO model is built around coordination. Your PCP is your main point of contact. This person knows your history, tracks your screenings, and helps manage your medications.
In-Network Care Comes First
With most HMO plans, you must use in-network providers for non-emergency care. Medicare.gov notes a few exceptions. These include emergency care, urgent care when you are out of the plan area, and short-term dialysis while you travel. If you go out of network without approval, you may owe the full cost.
Choosing a Primary Care Provider
Most Medicare Advantage HMOs ask you to select a PCP. Your PCP can handle checkups, chronic condition care, and prevention. In most plans, your PCP also provides referrals to specialists. Some services, like yearly screening mammograms, may not need a referral. Rules vary, so read your plan documents.
Referrals and Prior Authorization
Referrals and prior authorization are two different things. A referral is your PCP's recommendation to see a specialist. Prior authorization is the plan's approval for certain tests, procedures, or drugs. Ask both your doctor and your plan which services need approval. This simple step can save you from surprise bills.
HMO vs. HMO-POS: What Is the Difference?
Some BCBS plans are HMO-POS plans. POS means Point of Service. These plans may allow certain out-of-network services, usually at a higher cost. Not every HMO offers this feature. The table below shows the key differences.
|
Feature |
Standard HMO |
HMO-POS |
|---|---|---|
|
Network use |
In-network required for non-emergency care |
In-network preferred; some out-of-network allowed |
|
PCP selection |
Usually required |
Usually required |
|
Specialist referrals |
Often required |
Often required for in-network care |
|
Out-of-network cost |
Typically not covered |
Covered for some services at higher cost |
|
Best for |
People who want lower costs and coordinated care |
People who want a little more flexibility |
Check the Evidence of Coverage for your exact plan. It spells out which services fall under each rule.
What Do These Plans Cost?
Costs differ widely by location. A 2026 BCBS Michigan BCN Advantage HMO-POS example lists a $20 in-network PCP office visit copay and a $125 individual in-network deductible. A 2026 Blue Cross & Blue Shield of Rhode Island example lists several plans with $0 PCP copays. These are local examples only. They do not apply to every BCBS plan.
When you compare plans, look at more than the monthly premium. Review these items:
- PCP visit copay or coinsurance
- Specialist visit costs
- Annual deductible, if any
- Annual out-of-pocket maximum
- Prescription drug tiers and pharmacy network
- Telehealth costs and access
A plan with a low premium can still cost more if the copays are high or your doctor is not in the network.
Primary Care and Preventive Benefits to Look For
Prevention is where a good plan and a good PCP work best together. Medicare Advantage plans cover the preventive services Original Medicare covers. Many add extras. Common items include:
- Annual Wellness Visit: A yearly review of your health risks, medications, and care goals.
- Cancer screenings: Mammograms, colorectal screenings, and other tests based on your age and risk.
- Vaccines: Flu, pneumonia, and other recommended shots.
- Chronic condition support: Care for diabetes, high blood pressure, and heart disease.
- Supplemental extras: Some plans add vision, dental, hearing, or fitness benefits. These are plan-specific.
To learn what a yearly visit includes, read our guide on what happens during an annual wellness visit. You can also review the common Medicare wellness visit mistakes to avoid.
Why Your PCP Matters More in an HMO
In an HMO, your PCP is the hub of your care. A strong PCP relationship can lead to better results and fewer gaps. Your PCP can spot problems early, manage chronic illness, and guide you to the right specialist when needed. Learn more about how primary doctors help manage chronic illnesses.
Coordinated care also reduces repeated tests and conflicting prescriptions. This is especially helpful for older adults who see several providers. See why coordinated care beats fragmented care.
How to Check If Your Doctor Is In-Network
Networks change often. Do not rely on a doctor's website alone. Follow these steps before you enroll or book a visit:
- Find the exact plan name and plan ID on your member card or enrollment materials.
- Use the provider directory on your local BCBS company website.
- Search for your PCP, key specialists, preferred hospital, and pharmacy.
- Call the doctor's office and ask if they accept your exact plan and are taking new patients.
- Call the plan to confirm network status in writing, if possible.
- Ask about referral and prior authorization rules for services you use often.
If you need help with the search, our article on finding doctors accepting new patients offers practical tips. You can also read how to find the best Medicare HMO doctor in Riverview.
Common Mistakes to Avoid With a Medicare HMO
Many members run into the same problems. Knowing them ahead of time helps you avoid extra costs.
- Assuming your doctor is covered. Always verify before you enroll.
- Skipping the referral. A missed referral can lead to a denied claim.
- Using out-of-network care by habit. Non-emergency out-of-network visits may not be covered.
- Ignoring yearly plan changes. Benefits and costs can change each plan year.
- Forgetting the drug list. Check that your medications are on the plan's formulary.
For a deeper look, see four Medicare HMO doctor mistakes that hurt your care and how to use a Medicare HMO for better primary care.
Who May Benefit Most From a BCBS Medicare Advantage HMO?
An HMO can be a good fit if you:
- Want one main doctor to coordinate your care
- Prefer predictable copays
- Already see providers inside the plan network
- Value built-in extras like drug coverage or wellness perks
It may be a weaker fit if you travel often, split time between states, or want to see any doctor without checking a network. In that case, compare other Medicare options before you decide.
Primary Care Support in Tampa and Riverview
If you live in the Tampa Bay area, you need a clinic that makes Medicare easier. InCare's primary care services combine modern technology with personal attention. The team focuses on prevention, chronic condition care, and whole-body wellness. InCare offers services from cancer screenings to metabolic testing, so many needs can be handled in one place.
InCare has locations in Tampa and Riverview, plus virtual visits for added convenience. Patients praise the friendly staff and the quality of care. You can see what patients say when you visit us on Google — InCare. The clinic holds a 4.8 out of 5 rating from 359 reviews.
Plan acceptance varies, so always confirm that InCare participates in your exact plan before you schedule. Our front desk can help you check. To learn more about our Medicare focus, read seven traits of the best Medicare provider for primary care. You can also meet our providers and follow us on Instagram, Facebook, and TikTok for health tips.
Smart Questions to Ask Before You Enroll
Use this short list when you talk with a plan representative or your doctor's office:
- Is my PCP in the network for this exact plan?
- Do I need a referral to see a specialist?
- What is my copay for a PCP visit and for urgent care?
- What is the annual out-of-pocket maximum?
- Are my prescriptions covered, and at what tier?
- Which preventive and wellness benefits are included?
- What happens if I need care while traveling?
Write down the answers. Compare at least two or three plans side by side before you choose.
Take the Next Step With Confidence
A Blue Cross Blue Shield Medicare Advantage HMO can offer strong value when it matches your doctors, your budget, and your health goals. The key is to verify the network, understand the referral rules, and review the full cost picture for your county and plan year. A trusted primary care team makes every step easier.
Ready to build a care plan around your Medicare coverage? Book your visit with InCare today or contact our team with questions about coverage. We will help you get the personalized, prevention-focused care you deserve.
FAQs
Q: What is a Blue Cross Blue Shield Medicare Advantage HMO plan?
A: It is a private Medicare Part C plan offered by a local Blue Cross Blue Shield company. It covers Medicare Part A and Part B benefits through a defined provider network. Many plans also include drug coverage and extra benefits that vary by plan.
Q: Do I need to choose a primary care doctor with a BCBS Medicare Advantage HMO?
A: Most Medicare Advantage HMOs ask you to select a primary care provider. Your PCP coordinates your care and, in most plans, provides referrals to specialists. Confirm the exact rules in your plan's Evidence of Coverage.
Q: Can I see a doctor outside my BCBS Medicare Advantage HMO network?
A: Generally, you must use in-network providers for non-emergency care. Exceptions usually include emergency care, out-of-area urgent care, and temporary out-of-area dialysis. Some HMO-POS plans allow limited out-of-network care at a higher cost.
Q: How can I check whether my doctor accepts my BCBS Medicare Advantage HMO?
A: Search the provider directory on your local BCBS company website using your exact plan name. Then call the doctor's office to confirm they accept your plan and are taking new patients. Networks can change, so verify before each plan year.
Q: How much does a BCBS Medicare Advantage HMO cost?
A: Costs vary by state, county, and plan. Review the monthly premium, PCP copay, specialist costs, deductible, and annual out-of-pocket maximum. Benefits and costs can change each plan year, so check current documents.