Key Takeaways
- KP-10 is informal shorthand for a $10 copay on in-network primary care visits, not an official insurance term, so plans with identical names can have drastically different benefits and coverage details.
- Evaluate plans by comparing total annual costs (premiums, deductibles, coinsurance, out-of-pocket maximums) rather than focusing on the low copay alone, as a $10 primary care visit doesn't cover specialist, urgent care, lab, or imaging costs.
- Always verify that your preferred primary care provider accepts the plan and review the Summary of Benefits and Coverage document directly with your insurer before enrolling to avoid surprise bills and coverage gaps.
- Distinguish between KP-10 insurance plans and kisspeptin-10 (an unapproved experimental peptide), as confusing the two could lead to costly mistakes or exposure to unverified online products claiming hormone-related benefits.
Searching for a "top rated KP-10" plan can feel confusing. The term shows up in insurance paperwork, online forums, and even peptide research articles. That mix of meanings makes it hard to know what you are actually comparing. If you are trying to find affordable primary care in Tampa or Riverview, you need clear answers, not guesswork.
This guide breaks down what KP-10 really means in health insurance. It also explains why the term sometimes gets confused with kisspeptin-10, an unrelated research peptide. By the end, you will have a practical checklist for judging any plan that claims a low-cost primary care copay. You will also understand why working with a trusted clinic like InCare matters more than chasing a catchy plan label.
1. Understand What KP-10 Actually Means
KP-10 is not an official insurance term. It is informal shorthand people use to describe a health plan with a $10 copay for certain in-network primary care visits. No national agency or standard rating system defines "KP-10" as a specific product. This means two plans both called "KP-10" by patients could have very different benefits.
The confusion grows because KP-10 sometimes gets mixed up with Kaiser Permanente, a large health system. The letters "KP" happen to overlap, but a $10 copay plan is not automatically connected to any single insurer. Always confirm your plan's real name and details directly with your insurance card or member handbook.
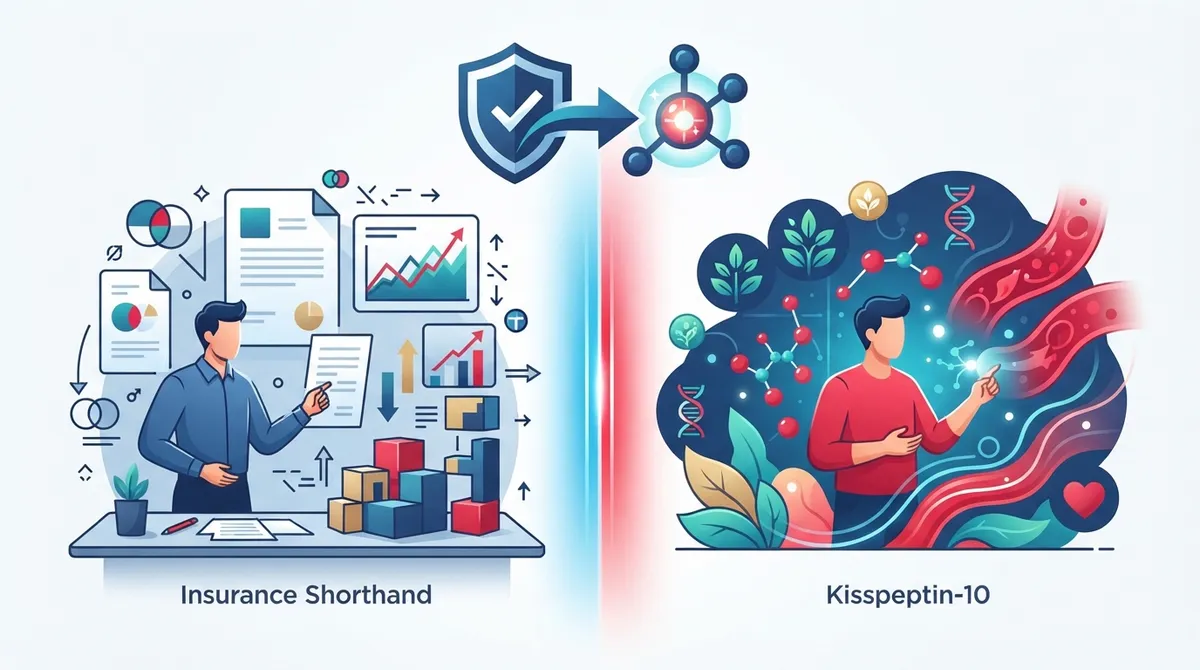
2. Know the Difference Between Insurance Shorthand and Kisspeptin-10
There is a second, completely separate meaning for KP-10. Kisspeptin-10 is a 10-amino-acid peptide, also called a decapeptide, studied for its role in reproductive hormone signaling. It activates a pathway known as KISS1R/GPR54, which can trigger the release of gonadotropin-releasing hormone in the brain.
This peptide is investigational. It is not an approved treatment for humans. Research remains limited to small clinical studies and lab experiments. You can learn more about how this peptide is discussed in wellness circles through this independent peptide research resource. If you see "KP-10" advertised as a supplement or injection online, that is a red flag, not a rated healthcare product.
Why This Distinction Matters for Your Health
Confusing an insurance copay term with an experimental peptide could lead to costly mistakes. Someone searching for an affordable doctor visit might stumble onto peptide marketing instead. Always clarify which KP-10 you mean before making any healthcare decision. For questions about primary care costs, our primary care services page can help clear up confusion.
3. Check the Summary of Benefits and Coverage
The only reliable way to judge a KP-10 plan is to read your Summary of Benefits and Coverage (SBC). This document lists exact costs for visits, labs, and procedures. It also spells out deductibles and any referral requirements.
Do not rely on a plan nickname alone. A $10 copay for primary care does not mean every service costs $10. Specialist visits, urgent care, imaging, and prescriptions often carry separate fees. Review your Evidence of Coverage or member handbook before scheduling any appointment.
4. Compare Total Annual Costs, Not Just the Copay
A low copay looks attractive, but it only tells part of the story. A truly top rated KP-10 plan should be judged on total yearly costs. This includes premiums, deductibles, coinsurance, and out-of-pocket maximums.
Here is a simple framework for comparing plans:
- List the monthly premium for each plan option.
- Add the deductible amount you must pay before coverage kicks in.
- Check the copay for primary care, specialist, and urgent care visits.
- Review coinsurance percentages for labs, imaging, and procedures.
- Confirm the annual out-of-pocket maximum.
- Add up a realistic yearly cost based on your health needs.
This method gives you a clearer picture than focusing on one number alone.
5. Verify Provider Network Access
A $10 copay means little if your preferred doctor is out of network. Before choosing a plan, confirm that your primary care provider accepts it. Call the clinic directly or check the insurer's online directory.
At InCare, our team helps patients understand how their insurance applies to visits at our Tampa and Riverview locations. We also welcome new patients exploring whether they need a primary care provider in the first place.
Questions to Ask Before You Enroll
- Does this plan cover annual wellness visits at no extra cost?
- Are lab tests and screenings included in the primary care copay?
- Do I need a referral to see a specialist?
- What happens if I visit an out-of-network provider by mistake?
- Is telehealth included under the same copay structure?
Asking these questions upfront can save you from surprise bills later.
6. Prioritize Preventive Care Coverage
Top rated plans, regardless of copay size, should include strong preventive care benefits. This includes annual physicals, cancer screenings, and basic lab work. Federal guidelines often require certain preventive services at no cost under many plans.
Preventive care catches problems early and reduces long-term costs. InCare offers cancer screening services designed to detect issues before they become serious. Pairing a good insurance plan with a proactive care team gives you the best long-term outcome.
7. Evaluate Member Experience and Support
Insurance ratings and reviews matter, but so does your actual experience getting care. A top rated KP-10 plan should come with responsive customer service, easy claims processing, and clear billing.
The same principle applies to choosing a clinic. Patient experience counts. InCare holds a 4.8 out of 5 rating on Google from hundreds of patients who value our friendly staff and thorough care. You can visit us on Google — InCare to read real patient feedback before your first visit. You can also follow our updates and patient stories on Facebook and Instagram.
8. Work With a Primary Care Team That Explains Your Benefits
The best way to avoid confusion about KP-10 or any insurance term is to partner with a clinic that takes time to explain your coverage. Our providers, including Dr. Naveen Paddu, Dr. Pramjeet Ahluwalia, and Dr. Teshy John, help patients understand exactly what their insurance covers before treatment begins.
We also offer resources like how to decode KP-10 copays in your health plan and a deeper look at what this insurance term really means. These guides walk you through real examples so you can make informed choices without guessing.
What to Do If You See KP-10 Peptide Products Online
If you come across kisspeptin-10 sold as an injectable or supplement, proceed with caution. Research shows this peptide affects hormone signaling, but human safety data remains limited. A 2025 preclinical study on cartilage cells and a 2015 lab study on breast cancer cells looked at kisspeptin-10 in test tubes, not in approved human treatments.
Products labeled "for research use only" should never be self-administered. If you have questions about hormone health or fertility concerns, speak with a licensed primary care provider first. Our team can guide you toward safe, evidence-based options rather than unverified online products. You can also see patient education content on our Tik Tok page.
Building Your Own KP-10 Comparison Checklist
Use this quick checklist before choosing any plan described as KP-10:
- Confirm the exact copay amount in writing from your insurer.
- Check which services fall under that copay.
- Review the deductible and out-of-pocket maximum.
- Verify your primary care doctor is in network.
- Ask about referral rules for specialists.
- Look at preventive care and screening coverage.
- Read patient reviews of both the insurer and the clinic.
This checklist helps you avoid relying on a nickname and instead focus on real plan details.
Final Thoughts on Choosing a Top Rated KP-10 Plan
There is no official ranking system for KP-10 health plans. The term is shorthand, not a guarantee of quality. The smartest approach is comparing total costs, provider access, and preventive care benefits across your options. Always verify details directly with your insurer before assuming a low copay covers everything.
At InCare, we help patients in Tampa and Riverview understand their coverage and get the care they need without confusion. Whether you are managing a chronic condition, scheduling a wellness visit, or exploring weight loss programs, our team is ready to help. Ready to get answers about your coverage and find a provider who truly listens? Book your appointment today or reach out to our team with any questions about your plan.
FAQs
Q: What does KP-10 mean in health insurance?
A: KP-10 is informal shorthand for a health plan featuring a $10 copay on certain in-network primary care visits. It is not a standardized insurance product name, so benefits vary by insurer, employer, and plan year. Always check your plan documents for exact terms.
Q: Does a KP-10 plan really make all primary care visits cost only $10?
A: A $10 copay typically applies only to eligible in-network primary care office visits. Specialist care, urgent care, lab work, imaging, and prescriptions usually have separate costs. Review your Summary of Benefits and Coverage to confirm what is included.
Q: Is KP-10 the same as a Kaiser Permanente health plan?
A: No. KP-10 is not officially tied to Kaiser Permanente despite the shared letters. It is a general term some patients use to describe a low-copay primary care benefit, regardless of the insurance carrier.
Q: What is kisspeptin-10, and is it FDA-approved?
A: Kisspeptin-10 is a 10-amino-acid investigational peptide studied for its role in reproductive hormone signaling. It is not FDA-approved for human treatment, and current evidence comes mostly from small studies and laboratory research.
Q: How can I verify whether my doctor accepts a KP-10 plan?
A: Contact your insurance provider directly or check their online network directory. You can also call your preferred clinic, such as InCare, to confirm they accept your specific plan before scheduling an appointment.