Key Takeaways
- UnitedHealthcare Medicare Supplement plans work alongside Original Medicare to cover deductibles, copayments, and coinsurance; they require both Medicare Part A and Part B enrollment to purchase.
- Plan G offers broad predictable coverage after the Part B deductible, while Plan N has lower premiums but requires copayments for office and ER visits—compare the premium difference against your expected copay costs to choose.
- Medigap does not cover dental, vision, hearing aids, or long-term care; fitness programs and dental discounts advertised are separate extras, not insurance benefits, and vary by location.
- Medigap cannot be used with Medicare Advantage; you must choose either Original Medicare plus a supplement plan for broader doctor choice, or Medicare Advantage with network-based care.
Turning 65 brings a long list of choices. One of the biggest is how to cover the costs that Original Medicare leaves behind. Deductibles, copayments, and coinsurance can add up fast, especially if you see your doctor often. That is where UnitedHealthcare Medicare Supplement plans come in.
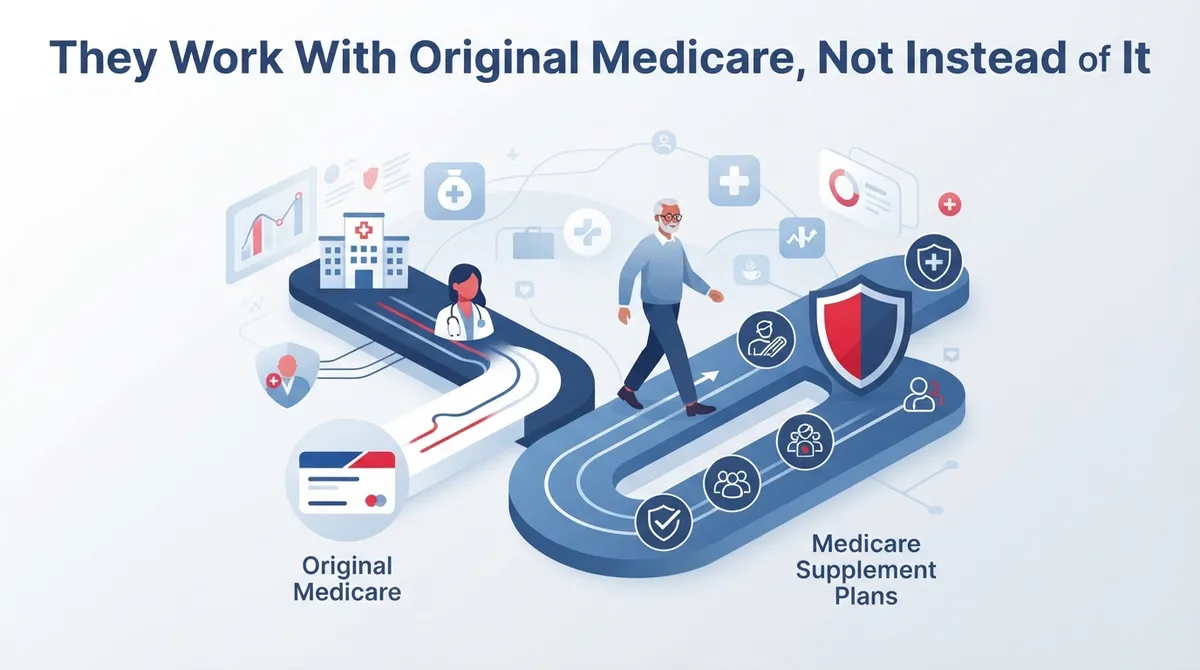
These plans, also called Medigap, are private policies that work alongside Original Medicare. They do not replace it. They help pay certain out-of-pocket costs when you see a primary care doctor, get a screening, or visit a specialist. For anyone who values steady, preventive care, that support matters.
This guide explains eight key facts about UnitedHealthcare Medicare Supplement plans in 2026. You will learn how they work, which plans are available, what they cover, and what they do not. You will also see how they connect to primary care and wellness. Rules, prices, and extras vary by state and plan year, so always confirm current details before you enroll.
1. They Work With Original Medicare, Not Instead of It
UnitedHealthcare Medicare Supplement plans are private insurance. They are sold by UnitedHealthcare and include AARP-branded plans insured by UnitedHealthcare Insurance Company. Their job is simple. They help pay part of what Original Medicare does not.
To buy a Medigap policy, you generally need both Medicare Part A and Part B. Medicare pays its share first. Then your supplement plan pays its share of the remaining approved costs, based on the plan letter you choose.
According to the Medicare & You 2026 handbook, Medigap benefits are standardized by letter. Premiums, however, vary by insurer and location. This means two people in different states can pay very different prices for the same plan letter.
2. Several Standardized Plan Letters Are Available
UnitedHealthcare's comparison information lists Plans A, B, G, K, L, and N for eligible applicants. Each letter offers a set of benefits that stays the same no matter which insurer sells it. Availability can differ by state.
Plans C and F are generally open only to people who were first eligible for Medicare before January 1, 2020. If you became eligible after that date, these plans are usually not an option.
Here is a quick overview of the plans commonly shown for new enrollees:
|
Plan |
General Approach |
Best Suited For |
|---|---|---|
|
Plan A |
Basic core benefits |
People who want the lowest coverage level |
|
Plan B |
Core benefits plus Part A deductible help |
Those who want a bit more hospital support |
|
Plan G |
Broad coverage after the Part B deductible |
People who want predictable costs |
|
Plan N |
Broad coverage with some copayments |
Those who accept small visit copays for a lower premium |
|
Plan K |
Partial cost sharing with an out-of-pocket limit |
People comfortable sharing more costs |
|
Plan L |
Higher cost sharing than K, with a lower limit |
Those who want a middle path |
UnitedHealthcare's 2025 comparison page lists an out-of-pocket limit of $7,220 for Plan K and $3,610 for Plan L. Check these figures against the current plan year and your state before you decide.
3. Plan G and Plan N Are the Most Compared Options
Many people weigh Plan G against Plan N. The difference comes down to premiums versus predictability.
Plan G
Plan G covers many Medicare-approved Part A and Part B cost-sharing amounts. You pay the Part B deductible first. After that, your covered costs are largely handled. This makes it easier to budget for frequent doctor visits.
Plan N
Plan N also covers many costs. But it can require copayments for certain office visits and emergency room visits. It also does not cover Part B excess charges. In return, premiums are often lower than Plan G.
If you see your primary care doctor several times a year, add up the possible copays. Then compare that total to the premium gap between the two plans.
4. Preventive Care Starts With Medicare Part B
Here is a point many people miss. Your preventive care coverage comes from Original Medicare, not from the Medigap plan itself. Part B covers many preventive services, including:
- The Welcome to Medicare visit
- The annual wellness visit
- Eligible screenings and counseling
Medicare.gov states that most covered preventive services cost nothing when you get them from a provider who accepts assignment. Cost sharing may apply to some services. It can also apply when a preventive service is combined with a non-preventive one.
A Medigap plan may help with cost sharing when Medicare applies it. But it does not create coverage for services Medicare excludes. To learn what a yearly visit looks like, read what happens during an annual wellness visit.
5. Extras Like Fitness and Discounts Are Not Insurance Benefits
UnitedHealthcare advertises certain member extras with some AARP Medicare Supplement plans. These may include a fitness program such as Renew Active. They may also include discounts on dental, hearing, and vision services.
These offers are not insurance coverage. They are separate from the insured plan benefits. They may vary by location and can change over time. Always confirm current terms and local networks with the insurer.
Here are some figures UnitedHealthcare has shared on its wellness extras page, updated in 2025:
- Dentegra in-network dental discounts generally average 30 to 40 percent off contracted rates.
- The dental discount network lists about 29,000 dentists and specialists at 130,000 locations.
- Hearing aid discounts of up to 20 percent, with added offers on select products.
Remember, a discount is not the same as insurance. It lowers a price. It does not pay a claim.
6. Medigap Does Not Cover Everything
Medigap has limits. Generally, it does not cover routine dental care, vision care, hearing aids, or long-term care. If you expect to need these services, plan for them separately.
A good habit is to review your health needs before choosing a plan. Ask yourself a few questions:
- How often do I see my primary care doctor each year?
- Do I take regular prescriptions?
- Do I have chronic conditions that need close monitoring?
- Would I rather pay a higher premium or face small copays?
Your answers help you see whether a plan like G or N fits your budget and routine. Medigap also does not include prescription drug coverage on its own, so many people look at a separate drug plan.
7. Medigap Cannot Be Used With Medicare Advantage
This rule surprises many people. Medigap policies do not work with Medicare Advantage. You generally cannot use a Medigap plan to pay Medicare Advantage cost sharing.
These are two different paths:
- Original Medicare plus Medigap: You can see any doctor who accepts Medicare, and the supplement helps with cost sharing.
- Medicare Advantage: A private plan replaces Original Medicare and often uses provider networks.
If you want broad freedom to choose doctors, Original Medicare with a supplement may appeal to you. If you like network-based care, you may look at other options. To understand the network side, see this guide on what a Medicare HMO is and how it works.
8. Costs and Enrollment Timing Both Matter
Premiums for UnitedHealthcare Medicare Supplement plans vary by state, plan letter, age, and other factors. Rates can also change from year to year. Underwriting rules differ by state, so verify local details before you enroll.
Timing matters too. Many people get the best access during their Medigap open enrollment period. This window generally begins when you are 65 or older and enrolled in Part B. During this time, you can typically buy a plan without medical underwriting. Outside that window, an insurer may ask health questions and may decline or charge more.
If you plan to enroll, follow these steps:
- Confirm you have Medicare Part A and Part B.
- Note your Medigap open enrollment dates.
- Compare plan letters that fit your needs and budget.
- Check premiums and any state-specific rules.
- Verify current extras and terms with the insurer.
How Primary Care Supports Your Medicare Plan
Insurance is only one part of good health. The other part is the doctor who knows you. A trusted primary care team helps you use your Medicare benefits well. They can schedule your wellness visit, order eligible screenings, and manage ongoing conditions.
At InCare, the focus is on prevention and whole-body health. The clinic serves patients in Tampa and Riverview, Florida, with primary care, urgent care, cancer screening, and advanced wellness services. You can learn more about how primary care supports long-term health. You can also read how Medicare coverage works for seniors in primary care.
Patients also value the friendly staff and personal attention. See what others say by reading InCare reviews on Google at Visit us on Google — InCare. For updates and health tips, you can follow the clinic on Facebook, Instagram, and TikTok.
If you are still choosing between coverage paths, this resource on Medicare Advantage plans and primary care may help you compare.
Final Thoughts
UnitedHealthcare Medicare Supplement plans can make healthcare costs easier to plan. They work with Original Medicare, offer several standardized plan letters, and may reduce the sting of deductibles and copays. Still, they do not cover everything, and extras like fitness and dental discounts are separate from insurance benefits.
Take time to compare plans, confirm details in your state, and pair your coverage with a primary care team you trust. Prevention, regular checkups, and clear communication with your doctor make any plan work harder for you.
Ready to take charge of your health? Book your visit with InCare today, or contact our team with your questions about primary care in Tampa and Riverview.
FAQs
Q: What does a UnitedHealthcare Medicare Supplement plan cover?
A: It helps pay certain Original Medicare costs, such as deductibles, copayments, and coinsurance. The exact benefits depend on the standardized plan letter you choose and your state. It does not replace Original Medicare.
Q: What is the difference between Plan G and Plan N?
A: Plan G covers many Medicare-approved cost-sharing amounts after you pay the Part B deductible. Plan N also covers many costs but can require copayments for certain office and emergency room visits. Plan N does not cover Part B excess charges.
Q: Does UnitedHealthcare Medigap cover dental, vision, hearing aids, or gym memberships?
A: Medigap generally does not cover routine dental, vision, hearing aids, or long-term care. UnitedHealthcare advertises discounts and fitness programs with some plans, but these are separate extras rather than insured benefits. Confirm current terms and availability with the insurer.
Q: Can I use a Medicare Supplement plan with Medicare Advantage?
A: No. Medigap policies do not work with Medicare Advantage. You generally cannot use a supplement plan to pay Medicare Advantage cost sharing.
Q: When can I enroll without medical underwriting?
A: Many people can enroll without medical underwriting during their Medigap open enrollment period. This window generally begins when you are 65 or older and enrolled in Part B. Rules can vary by state, so verify local details before you apply.