Key Takeaways
- A concierge doctor is a primary care physician who charges a recurring membership fee for a smaller patient panel, longer visits, and easier access, but the fee usually does not cover all medical care.
- Membership fees rarely replace insurance: copayments, deductibles, labs, imaging, specialists, medications, and hospital care may still be billed separately, so confirm these costs before enrolling.
- Medicare does not cover concierge membership fees, and a participating physician must follow Medicare billing rules for covered services, so Medicare patients should verify billing arrangements in advance.
- Before joining, get the service agreement in writing and ask what the fee includes, how after-hours and urgent needs are handled, what happens when the doctor is away, and how refunds and cancellations work.
If you have ever waited three weeks for a ten-minute appointment, you may have wondered whether there is a better way to get primary care. That question leads many people to ask, what is a concierge doctor? In simple terms, a concierge doctor is a primary care physician who charges a recurring membership fee in exchange for more access and a more personal experience.
The model is also called concierge medicine, retainer-based medicine, or boutique medicine. It has grown fast. One commercial estimate put the U.S. concierge medicine market at $8.14 billion in 2024, with a forecast of $17.16 billion by 2034 (StatifFacts, 2025). Estimates vary by research firm, but the trend is clear: more patients want time, access, and prevention-focused care.
This guide covers six things every patient should understand before joining a concierge practice in 2026. It is written for busy professionals, young families, wellness seekers, and anyone who wants a stronger relationship with a doctor in the Tampa Bay area.
1. What a Concierge Doctor Actually Is
A concierge doctor is typically a primary care physician who limits the size of their patient panel. Patients pay an annual or monthly fee, often called a retainer or membership. In return, they receive enhanced access and extra attention.
The fee generally pays for access or a defined set of services. It does not usually cover all medical care. Patients may still owe copayments, deductibles, and charges for tests, medications, specialists, emergency care, or hospital stays.
Here is a quick snapshot of the model:
- Membership fee: A recurring payment for access and defined services.
- Smaller panel: The doctor sees fewer patients, so each visit can be longer.
- Personalized planning: Care is built around your goals, history, and risks.
- Coordination: The practice helps connect you with specialists and services.
Benefits are not guaranteed by the label alone. Always read the written service agreement to see what a practice promises.
2. What Benefits You May Receive
Benefits differ from one practice to the next. Still, most members look for the same things: time, convenience, and a doctor who knows them well.
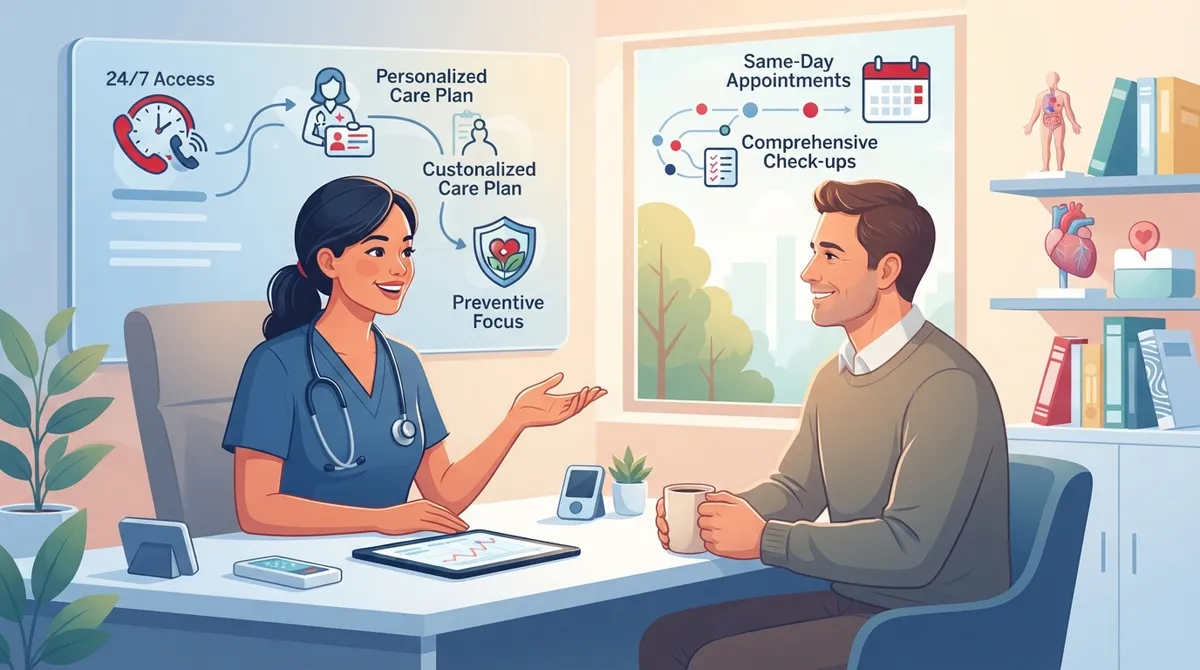
Common Membership Features
- Longer appointments that allow real conversation
- Easier or same-day scheduling
- Direct communication with your physician
- Telehealth and virtual visits
- Preventive-care planning and annual health reviews
- Help coordinating specialist care and test results
Be careful with big promises. Claims such as 24/7 availability should be verified directly with the practice. Ask who answers after hours, how fast messages are returned, and what happens when your physician is away.
For tech-savvy patients, virtual access matters. Many people now expect video visits, online messaging, and digital records. For families, easier scheduling can mean fewer missed work hours and school days.
3. Concierge Medicine vs. Direct Primary Care
People often mix up concierge medicine and direct primary care (DPC). The two models overlap, but they are not identical.
|
Feature |
Concierge Medicine |
Direct Primary Care |
|---|---|---|
|
Payment |
Membership fee plus insurance billing for covered care |
Patient fees for primary care, often no insurance billing |
|
Insurance role |
May continue to bill insurance for covered clinical services |
Generally does not bill insurance for primary care |
|
Typical fee level |
Often higher, varies widely |
Often lower, varies widely |
|
Panel size |
Usually smaller than traditional practices |
Usually smaller than traditional practices |
|
Best for |
Patients who want to keep insurance and gain more access |
Patients who want simple, flat-fee primary care |
Terms and models can blur together. The best step is to ask each practice exactly how it operates, what it bills, and what is covered by the fee.
4. What It Costs and What Insurance Covers
Prices vary substantially by practice. For example, Mass General Brigham lists an annual membership fee of $10,000 for its specific concierge program. That figure is one example, not a national average. Other practices charge much less, and some use monthly plans.
Here is how costs usually break down:
- Membership fee: Paid directly to the practice, usually not reimbursed by insurance.
- Insurance costs: Copayments and deductibles may still apply for covered services.
- Outside services: Labs, imaging, specialists, and hospital care may be billed separately.
- Medications: Prescriptions are generally not included in the fee.
Medicare does not cover concierge membership fees. A physician who participates in Medicare must follow Medicare billing rules for covered services, and the membership fee cannot be an extra charge for services Medicare already covers. Eligible clinical services may still be billed separately, subject to the usual rules and cost-sharing.
You can usually keep your regular health insurance while using a concierge doctor. Confirm this with the practice before you enroll.
5. Who May Benefit Most
Concierge-style care is not right for everyone. It tends to fit people who value time and proactive planning.
- Busy professionals and millennials: People who want virtual visits and quick answers without a long wait.
- Wellness seekers: Patients interested in advanced prevention, DNA gene testing, metabolic breath analysis, or body composition tracking.
- Young families: Parents who need one coordinated team for check-ups, screenings, and sick visits.
- Women focused on prevention: Patients who want wellness exams and screenings beyond reproductive care.
- Young adults: Gen Z patients who want prevention-focused guidance instead of piecing together advice online.
On the other hand, if you are healthy, rarely need care, and have a strong insurance plan, a high fee may not add enough value. Weigh the cost against how often you would truly use the extra access.
6. What to Ask Before You Join
Before you sign anything, treat the decision like any major healthcare choice. Ask clear questions and expect clear answers.
- What exactly does the fee include, and what does it exclude?
- Is insurance billed for covered visits, labs, and tests?
- How are urgent and after-hours needs handled?
- How are referrals, imaging, and lab work charged?
- What happens when my physician is out of the office?
- How do cancellation and refund policies work?
- How many patients does each physician serve?
Strong practices answer these questions openly and put the answers in writing.
A Practical Alternative: Personalized Primary Care at InCare
Many patients want the benefits of concierge care without confusion about fees and fine print. InCare's primary care services offer a personalized approach with locations in Tampa and Riverview, Florida. The team combines medical expertise with modern technology to focus on prevention and whole-body health.
InCare goes beyond routine visits. Patients can access cancer screenings, medical weight loss programs, DNA gene testing, and IV hydration and vitamin drips. Same-day needs are covered by urgent care, and virtual appointments are available for added convenience. You can learn more about concierge-style primary care in Tampa and meet the providers behind the care.
The results speak for themselves. InCare holds a 4.8 out of 5 rating on Google across 359 reviews, with patients praising the friendly staff and quality of care. You can read InCare reviews on Google to see what neighbors in Tampa and Riverview say. To follow wellness updates, visit InCare on Instagram, Facebook, or TikTok.
Conclusion
So, what is a concierge doctor? It is a primary care physician who offers enhanced access, longer visits, and personalized planning in exchange for a recurring membership fee. The model can be valuable, but costs, inclusions, and insurance rules vary widely. Always review the service agreement, confirm what Medicare and your insurance will and will not cover, and ask about after-hours care before you commit.
If you want personalized, prevention-focused care in the Tampa Bay area, InCare is an excellent place to start. Ready to experience a more attentive approach to your health? Book Now or contact our team to learn how InCare can support your goals in 2026.
FAQs
Q: What does a concierge doctor do?
A: A concierge doctor provides primary care to a limited number of patients who pay a recurring membership fee. Members often receive longer visits, easier scheduling, direct communication, and help coordinating specialist care. The exact services depend on the practice and its written agreement.
Q: Does Medicare cover concierge medicine?
A: Medicare does not cover concierge membership fees. A participating physician must follow Medicare billing rules, and the fee cannot be an extra charge for Medicare-covered services. Eligible clinical services may still be billed to Medicare separately, with normal cost-sharing.
Q: Can I keep my health insurance if I use a concierge doctor?
A: In most cases, yes. The membership fee pays for access or specified services, not all medical care. You may still owe copayments, deductibles, and charges for tests, medications, specialists, and hospital care, so confirm details with the practice.
Q: How is concierge medicine different from direct primary care?
A: Direct primary care usually relies on patient fees and generally does not bill insurance for primary care. Concierge practices may charge a membership fee and also bill insurance for covered clinical care. The models can overlap, so ask each practice how it operates.