Key Takeaways
- Aetna senior supplemental (Medigap) helps pay out-of-pocket costs for Original Medicare but does NOT cover prescriptions, dental, vision, or hearing aids—you need separate plans for these.
- Enrollment timing is critical: enroll during your Medigap Open Enrollment Period (age 65+ with Part B) to guarantee coverage; waiting risks medical underwriting, higher premiums, or denial.
- Plan G is the most common choice for new Medicare enrollees (those eligible after Jan 1, 2020) since Plans C and F are unavailable to them due to federal rules.
- Premiums vary significantly by state, ZIP code, age, and plan letter—always request a personal quote and review your state's Outline of Coverage before enrolling.
Medicare is a strong foundation for senior health, but it does not pay for everything. Deductibles, coinsurance, and copayments can add up fast. That is why many people search for an Aetna senior supplemental plan. For most readers, this phrase means Aetna Medicare Supplement Insurance, also called Medigap. It is private insurance that helps pay some of the costs Original Medicare leaves behind.
Understanding how this coverage works can change how you use your doctor. Predictable costs make it easier to keep annual visits, follow up on chronic conditions, and stay current on screenings. This guide covers 11 facts about Aetna senior supplemental coverage, with a focus on primary care and wellness. Plan availability and prices vary by state and by person, so always confirm current details with Aetna and Medicare.gov before you enroll.
1. Aetna Senior Supplemental Usually Means Medigap
The most common meaning of "Aetna senior supplemental" is Aetna Medicare Supplement Insurance. It works alongside Original Medicare (Parts A and B). It is not a replacement for Medicare, and it is not the same as a Medicare Advantage plan.
With Medigap, Medicare pays its share of approved costs first. Then your supplement pays its share based on the policy you chose. This two-step process is the core idea behind the coverage.
2. You Need Medicare Parts A and B First
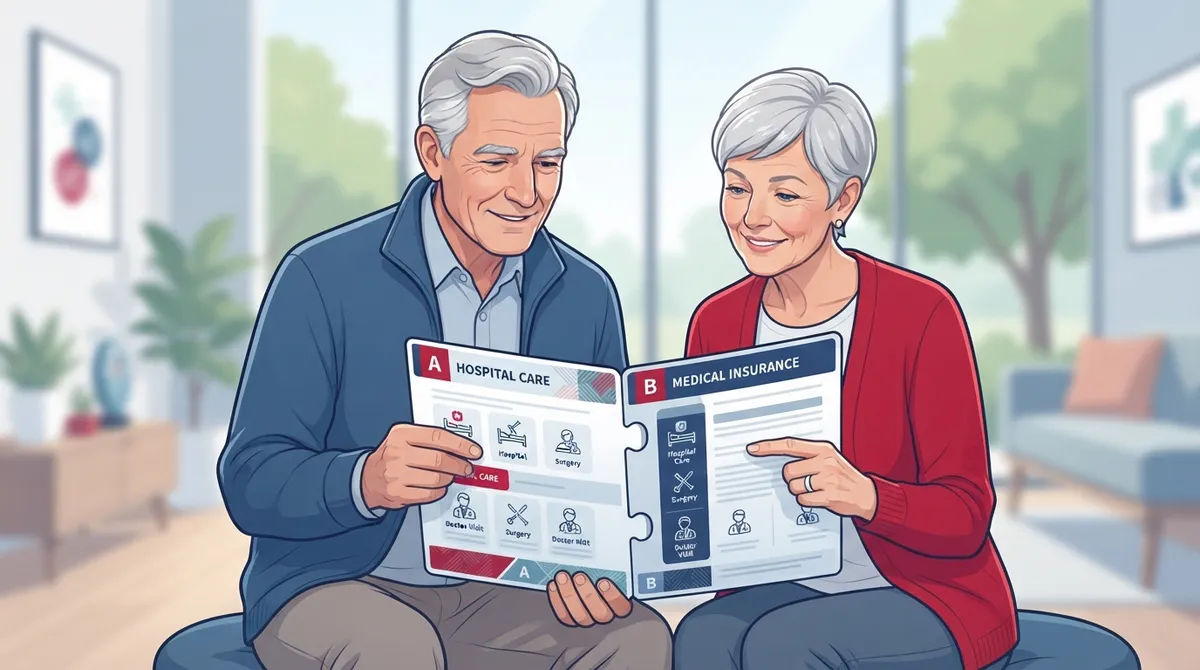
A Medigap policy generally requires enrollment in both Medicare Part A and Part B. You also keep paying your Part B premium. The Aetna premium is a separate monthly cost.
This matters for planning. Your total cost includes your Part B premium, your supplement premium, and any drug plan premium you add.
3. Plan Letters Are Standardized
In most states, Medigap plans are standardized by letter. A Plan G from one insurer offers the same basic benefits as a Plan G from another. Prices and availability, however, differ by state, ZIP code, and insurer.
Aetna's materials list options such as Plans A, F, G, and N in some locations. Check which plans Aetna offers where you live before you compare.
4. Plans C and F Are Limited for Newer Enrollees
People who became newly eligible for Medicare on or after January 1, 2020, generally cannot buy Plans C or F. These plans cover the Part B deductible, and federal rules no longer allow that for new enrollees.
Plan G is a common alternative. It does not cover the Part B deductible, but it fills many other gaps. For 2026, Medicare lists the annual Part B deductible at $202.90. Verify the current figure on Medicare.gov, since it can change.
5. Plan N Can Mean Small Copays
Plan N usually covers Part B coinsurance but may require copayments. These can be up to $20 for some office visits and up to $50 for emergency room visits that do not lead to a hospital stay. Exact benefits depend on the policy and state rules.
For primary care patients, this is a helpful detail. A small, known copay is easier to budget than an open-ended one.
6. Compare the Plans Side by Side
The table below offers a simple snapshot of several common options. It is a general guide, not a full benefits list. Always read the Outline of Coverage for your state.
|
Plan |
General Approach |
Part B Deductible |
Good to Know |
|---|---|---|---|
|
Plan A |
Basic coverage |
Not covered |
Fewer benefits, often lower premium |
|
Plan G |
Broad coverage |
Not covered |
Common choice for new enrollees |
|
Plan N |
Lower premium, shared costs |
Not covered |
May have copays for some visits |
|
Plan F |
Most complete coverage |
Covered |
Generally closed to those new to Medicare on or after 2020 |
|
Plans K and L |
Partial cost sharing |
Not covered |
Annual out-of-pocket limits of $8,000 (K) and $4,000 (L) in 2026 |
7. What Medigap Does Not Cover
Many people assume a supplement covers everything. It does not. Medigap generally excludes:
- Prescription drug coverage (you need a separate Part D plan)
- Routine dental care
- Routine vision care and eyeglasses
- Hearing aids
- Long-term care
A supplement also does not add new preventive benefits. It helps pay your share of services Medicare already covers. If Medicare does not cover a service, Medigap generally will not either.
8. It Helps With Primary Care and Preventive Costs
For primary care, Medigap can reduce your share of costs for covered Original Medicare services. That often includes many clinician visits and preventive services. This makes regular care more predictable.
Consistent care matters because it catches problems early. Steady visits help with blood pressure, diabetes, and cholesterol. To learn what a yearly visit involves, read about what happens during an annual wellness visit. You can also review what Medicare covers for seniors in primary care.
9. Medigap Is Different From Medicare Advantage
This is one of the biggest points of confusion. Medigap works with Original Medicare. Medicare Advantage replaces Original Medicare with a private plan that often has its own network and copays.
You generally cannot use a Medigap policy to pay Medicare Advantage cost sharing. Pick one path or the other. If you are weighing both, see this guide to Medicare Advantage plans and what primary care patients need to know.
One practical advantage of Medigap is provider choice. With Original Medicare and a supplement, you can generally see any doctor who accepts Medicare. That freedom appeals to patients who want a long-term relationship with a trusted physician. For help on this point, read how to find doctors accepting new patients near you.
10. Premiums Vary Widely by Location
Aetna premiums are separate from your Medicare Part B premium. They change based on location, age, and the rating method used. Aetna's Pennsylvania outline of coverage, for example, lists annual premiums effective June 1, 2026, that vary by ZIP code region, age, sex, and plan. It also notes a $20 one-time policy fee.
Those figures apply to that state only. A quoted premium in one place is not a national price. Request your own quote, and read your state's Outline of Coverage for current rates and underwriting rules.
11. Enrollment Timing Affects Your Options
When you enroll matters. During your Medigap Open Enrollment Period, you generally have a guaranteed right to buy a policy. This period typically begins when you are 65 or older and enrolled in Part B. Outside that window, insurers in many states may use medical underwriting. That can mean higher prices or a denied application.
Do not wait until a health problem appears. Early planning gives you more choices and lower stress.
How to Choose the Right Coverage: A Simple Process
- Confirm your Medicare enrollment. Make sure you have Parts A and B.
- List your health needs. Think about chronic conditions, expected visits, and budget.
- Check plan availability. Ask which plan letters Aetna offers in your ZIP code.
- Compare total costs. Add premiums, copays, and deductibles together.
- Add a drug plan. Medigap does not cover prescriptions.
- Read the Outline of Coverage. Verify rules and rates for your state.
Pairing Coverage With a Primary Care Partner
Insurance pays the bills, but a good doctor protects your health. The two work best together. A primary care team that knows your history can coordinate screenings, manage medications, and spot issues early. Learn more about what a Medicare doctor actually does for you, or explore 7 traits of the best Medicare provider for primary care.
InCare is a personalized clinic in Tampa and Riverview, Florida. The practice combines modern technology with hands-on medical expertise. Services include primary care, cancer screening, and urgent care, all built around prevention. Patients also rate the team highly; you can see what people say when you visit us on Google — InCare. For updates and wellness tips, follow the clinic on Instagram, Facebook, or TikTok.
Making Your Supplemental Plan Work Harder
Having coverage is only half the job. Using it well matters just as much. Try these habits:
- Schedule your annual wellness visit every year.
- Keep up with recommended screenings.
- Ask your doctor which services Medicare covers before you book.
- Review your plan each year for rate changes.
- Keep a list of your medications and questions before each visit.
These small steps help you get more value from your Aetna senior supplemental plan. They also help you stay healthy longer.
Final Thoughts
An Aetna senior supplemental plan can make Medicare costs easier to predict. It does not add new benefits, and it does not cover drugs, dental, vision, or hearing aids. Still, it can help you keep up with the regular care that protects your health. Check your state's plan options, compare total costs, and confirm details with official sources before you decide.
Ready to pair your coverage with a primary care team that puts prevention first? Book your visit with InCare today, or contact our team with questions about getting started.
FAQs
Q: What is Aetna senior supplemental insurance?
A: Aetna senior supplemental insurance usually refers to Aetna Medicare Supplement, also called Medigap. It is private insurance that helps pay certain out-of-pocket costs for people with Original Medicare (Parts A and B). Plan availability and benefits vary by state.
Q: Does Aetna Medicare Supplement cover prescriptions, dental, or vision?
A: No. Medigap policies generally do not include prescription drug coverage, routine dental, vision, or hearing aids. Most people add a separate Part D plan for medications. Check Medicare.gov and your plan documents for current details.
Q: What is the difference between Medigap and Medicare Advantage?
A: Medigap works alongside Original Medicare and helps pay your share of covered costs. Medicare Advantage replaces Original Medicare with a private plan that often has its own network and copays. You generally cannot use Medigap to pay Medicare Advantage cost sharing.
Q: How much does Aetna Medicare Supplement cost?
A: Premiums vary by state, ZIP code, age, plan letter, and rating method. They are separate from your Medicare Part B premium. Review your state's Outline of Coverage or request a personal quote for current rates.
Q: When can I enroll in a Medigap plan without being denied?
A: During your Medigap Open Enrollment Period, you generally have a guaranteed right to buy a policy. It typically starts when you are 65 or older and enrolled in Part B. After that window, many states allow medical underwriting, so approval and price may depend on your health.